


What Are The Medicare IRMAA Brackets And How to Avoid Them
By Danny Gudorf | Founder, Gudorf Financial Group | Updated August 2026
Every year we sit down with a client's tax return and find the same thing. A large IRA withdrawal, a stock sale, or a Roth conversion that made perfect sense on its own pushed them over a Medicare IRMAA bracket they did not know existed.
Nobody warned them. Two years later, the Social Security letter shows up with a higher premium, and they call us asking what happened.
So this post does three things. It gives you the actual 2026 Medicare IRMAA brackets in a table you can read, shows you where the 2027 and 2028 lines will probably land, and walks through how we keep clients under those lines on purpose.
What IRMAA Is, in Plain Language
IRMAA stands for Income-Related Monthly Adjustment Amount. It is a surcharge Medicare adds to your Part B and Part D premiums when your income goes above a set level.
Think about it this way. Everyone on Medicare pays the standard Part B premium, which is $202.90 a month in 2026.
If your income is high enough, Medicare adds an extra amount on top. That extra amount is IRMAA.
It is not a tax on your return. It comes straight out of your Social Security check, or you get billed for it, and it applies to each spouse separately.
If you want the full background on how the surcharge works, we cover that in our guide to what IRMAA is and how to reduce the surcharge. This post is about the brackets themselves and the planning around them.
The Two-Year Lookback: Why Your 2026 Income Sets Your 2028 Premium
Here is the part that trips people up. Medicare does not look at this year's income to set this year's premium.
It looks back two years. Your 2026 premium is based on the tax return you filed for 2024.
That means:
- 2026 premiums use your 2024 income
- 2027 premiums use your 2025 income
- 2028 premiums use your 2026 income
So if you are reading this in 2026 and wondering about the 2028 IRMAA brackets, the decision that matters is what you do with your income between now and December 31. The Roth conversion you make this fall shows up on a Medicare letter in late 2027.
That lag is why so many people get surprised. The income event and the bill are two years apart, and by the time the bill arrives most people have forgotten what caused it.
2026 Medicare IRMAA Brackets
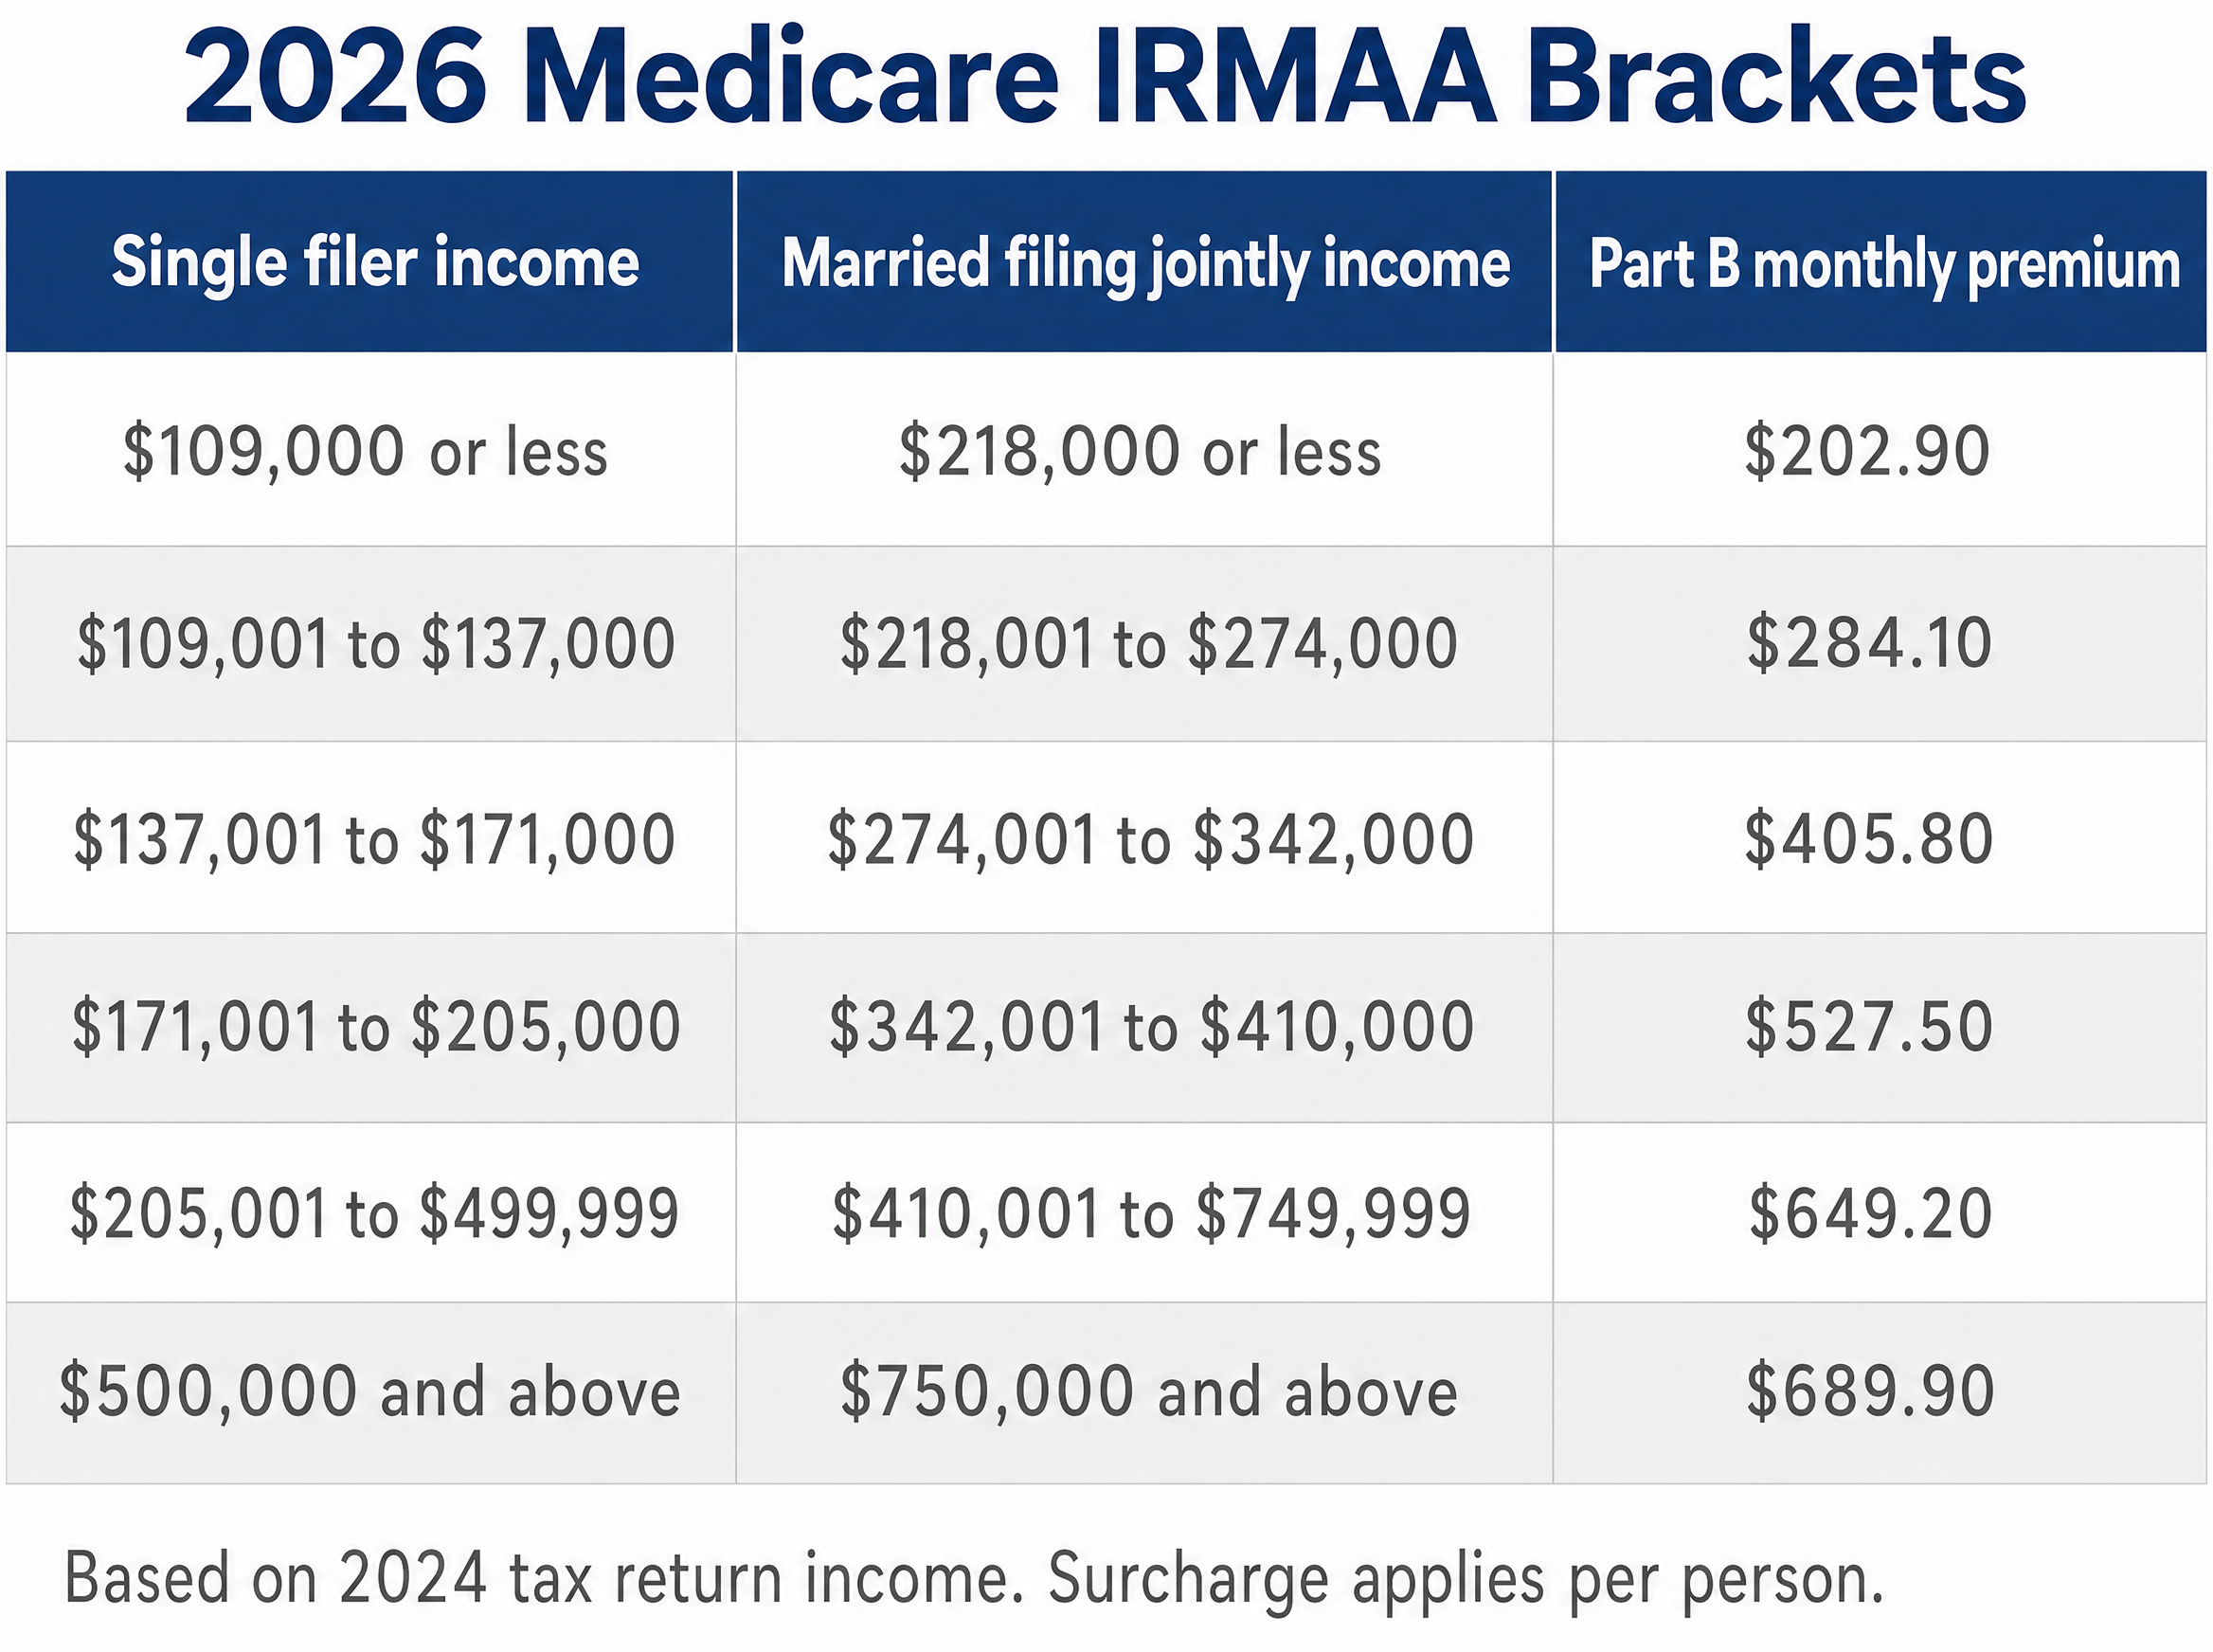
These are the official 2026 brackets from the Social Security Administration. The income number is your modified adjusted gross income, or MAGI, from your 2024 return.
Part B amounts below are your total monthly premium, standard plus surcharge. Part D amounts are the surcharge only, added on top of whatever your drug plan charges.
| 2024 MAGI, single filer | 2024 MAGI, married filing jointly | Part B total per month | Part B surcharge | Part D surcharge |
|---|---|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 | $0.00 | $0.00 |
| $109,001 to $137,000 | $218,001 to $274,000 | $284.10 | $81.20 | $14.50 |
| $137,001 to $171,000 | $274,001 to $342,000 | $405.80 | $202.90 | $37.50 |
| $171,001 to $205,000 | $342,001 to $410,000 | $527.50 | $324.60 | $60.40 |
| $205,001 to $499,999 | $410,001 to $749,999 | $649.20 | $446.30 | $83.30 |
| $500,000 and above | $750,000 and above | $689.90 | $487.00 | $91.00 |
Two things to notice. First, the surcharges are per person, so a married couple both on Medicare pays each amount twice.
Second, the top tier at $500,000 single and $750,000 joint is frozen by law. It does not move with inflation until at least 2028.
The married filing jointly thresholds
If you file jointly, your line is exactly double the single line. The first bracket starts at $218,001, and the next lines fall at $274,001, $342,001, $410,001, and $750,000.
Married filing separately is a different animal. Medicare uses the single thresholds, and above $109,000 you skip straight to the second-highest tier at $391,000.
Almost nobody should file separately on Medicare without running the numbers first.
IRMAA Case Studies: Two Households, Same Year
Let me show you how the 2026 brackets land on two real-life setups. Same tables, very different bills.
Case Study 1: Mary, single filer
Mary is a retired teacher. Her 2024 MAGI was $102,500, which puts her under the $109,000 single threshold.
- Part B: $202.90 per month, the standard 2026 premium
- Part D: her plan premium only, no surcharge
- IRMAA for 2026: $0
Now, Mary has about $6,500 of room under the line. One larger-than-normal IRA withdrawal in 2026 would use that up and set her 2028 premium at $284.10 a month.
Case Study 2: Bill and Barbara, married filing jointly
Bill and Barbara are both on Medicare. Their 2024 joint MAGI was $223,000, which is $5,000 over the $218,000 line and puts them in the second tier.
- Part B: $284.10 per month, per person ($202.90 standard plus $81.20 surcharge)
- Part D: their plan premium plus $14.50 per month, per person
- Extra cost: $95.70 per month, times two, times twelve
That works out to $2,296.80 more in 2026 Medicare premiums, $1,148.40 for each of them. And it came from $5,000 of income.
If they had done a $5,000 QCD instead of taking that last IRA withdrawal, or split a stock sale across two years, the surcharge would be zero. That is the whole reason we plan with a buffer.
Projected 2027 and 2028 IRMAA Brackets
The brackets below the top tier move with inflation every year. Medicare announces the official numbers each fall, so anything past 2026 is a projection.
We are making assumptions here. The 2027 numbers are close to final because most of the inflation data is already in.
The 2028 numbers depend on inflation through the summer of 2027. Treat them as a range, not a promise.
| Tier | 2026 (official) | 2027 (projected) | 2028 (projected) |
|---|---|---|---|
| Standard, single | $109,000 | $112,000 | $114,000 to $116,000 |
| Standard, joint | $218,000 | $224,000 | $228,000 to $232,000 |
| Second tier, single | $137,000 | $141,000 | $143,000 to $146,000 |
| Second tier, joint | $274,000 | $282,000 | $286,000 to $292,000 |
| Third tier, single | $171,000 | $176,000 to $177,000 | $179,000 to $182,000 |
| Third tier, joint | $342,000 | $352,000 to $354,000 | $358,000 to $364,000 |
| Fourth tier, single | $205,000 | $211,000 to $212,000 | $214,000 to $218,000 |
| Fourth tier, joint | $410,000 | $422,000 to $424,000 | $428,000 to $436,000 |
| Top tier, single / joint | $500,000 / $750,000 | $500,000 / $750,000 | $500,000 / $750,000 |
The practical point for 2028 planning: if you are a married couple, keep your 2026 MAGI under about $228,000 and you should be safe. If you are single, the line is around $114,000.
That "about" is doing real work. It is why we plan with a buffer, which I will get to in a minute.
Why One Dollar Over Costs You Thousands
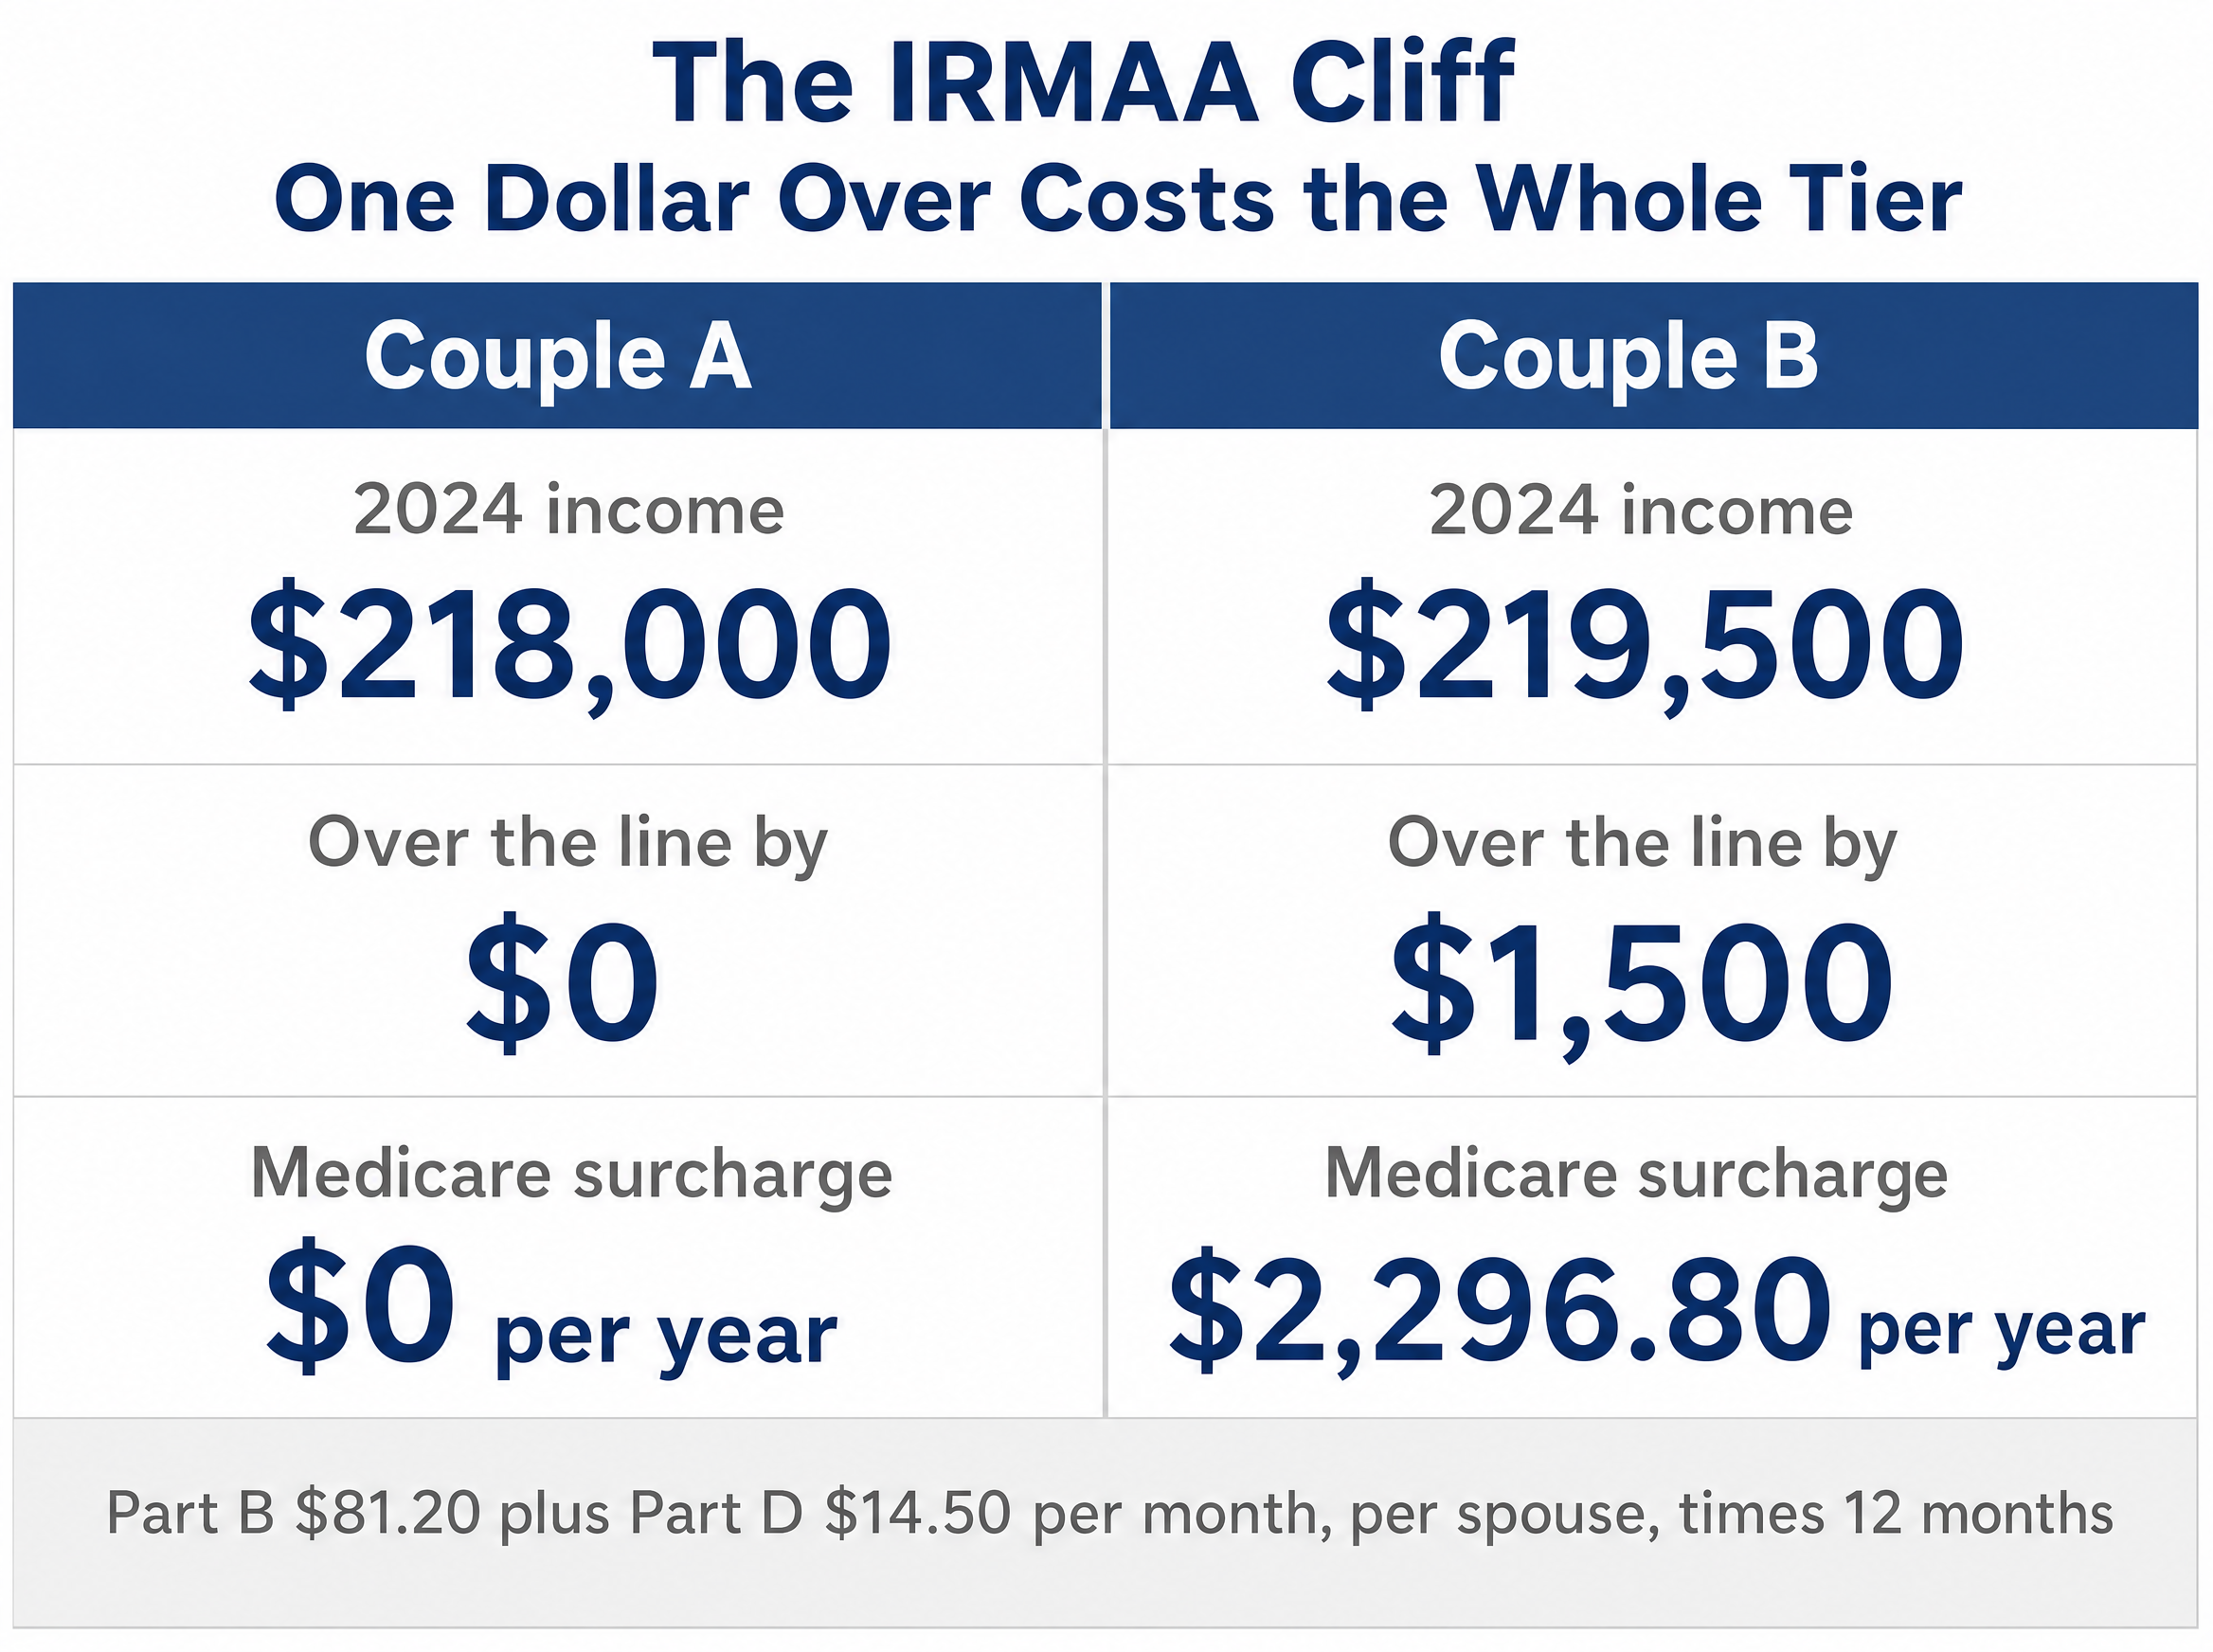
IRMAA is a cliff, not a slope. Income tax brackets only tax the dollars above the line.
IRMAA charges you the full tier surcharge the moment you cross it.
Let me show you what that looks like. Say a married couple, both on Medicare, had a 2024 MAGI of $219,500, which is $1,500 over the $218,000 line.
- Part B surcharge: $81.20 per month, per person
- Part D surcharge: $14.50 per month, per person
- Total: $95.70 per month, times two spouses, times twelve months
That $1,500 of extra income costs them $2,296.80 in 2026 Medicare premiums. Not a percentage of the overage, the whole tier.
Here is what happened with one of our clients before they started working with us. They pulled about $60,000 out of an IRA in the same year to finish a kitchen and replace a car.
Reasonable decisions, both of them.
Nobody told them that the withdrawal counted as income for Medicare. They crossed the joint threshold by roughly $9,000, and two years later they paid a full year of higher premiums for it.
The point is, IRMAA does not care why your income went up. An IRA withdrawal, a capital gain, a Roth conversion, and a bonus all look the same to Medicare.
How Medicare Calculates Your MAGI
Your IRMAA income is not the taxable income number at the bottom of your return. It is your adjusted gross income plus tax-exempt interest.
So a few things count that people forget about:
- Municipal bond interest. Tax-free on your return, but Medicare adds it back.
- The taxable portion of Social Security. The part that shows up in your AGI counts. The untaxed part does not.
- Capital gains distributions from mutual funds. Even if you did not sell anything yourself.
- Roth conversions. The converted amount is income in the year you convert.
Roth withdrawals, on the other hand, do not count. Neither do qualified charitable distributions, which is why they matter so much for this.
How We Keep Clients Under the Line
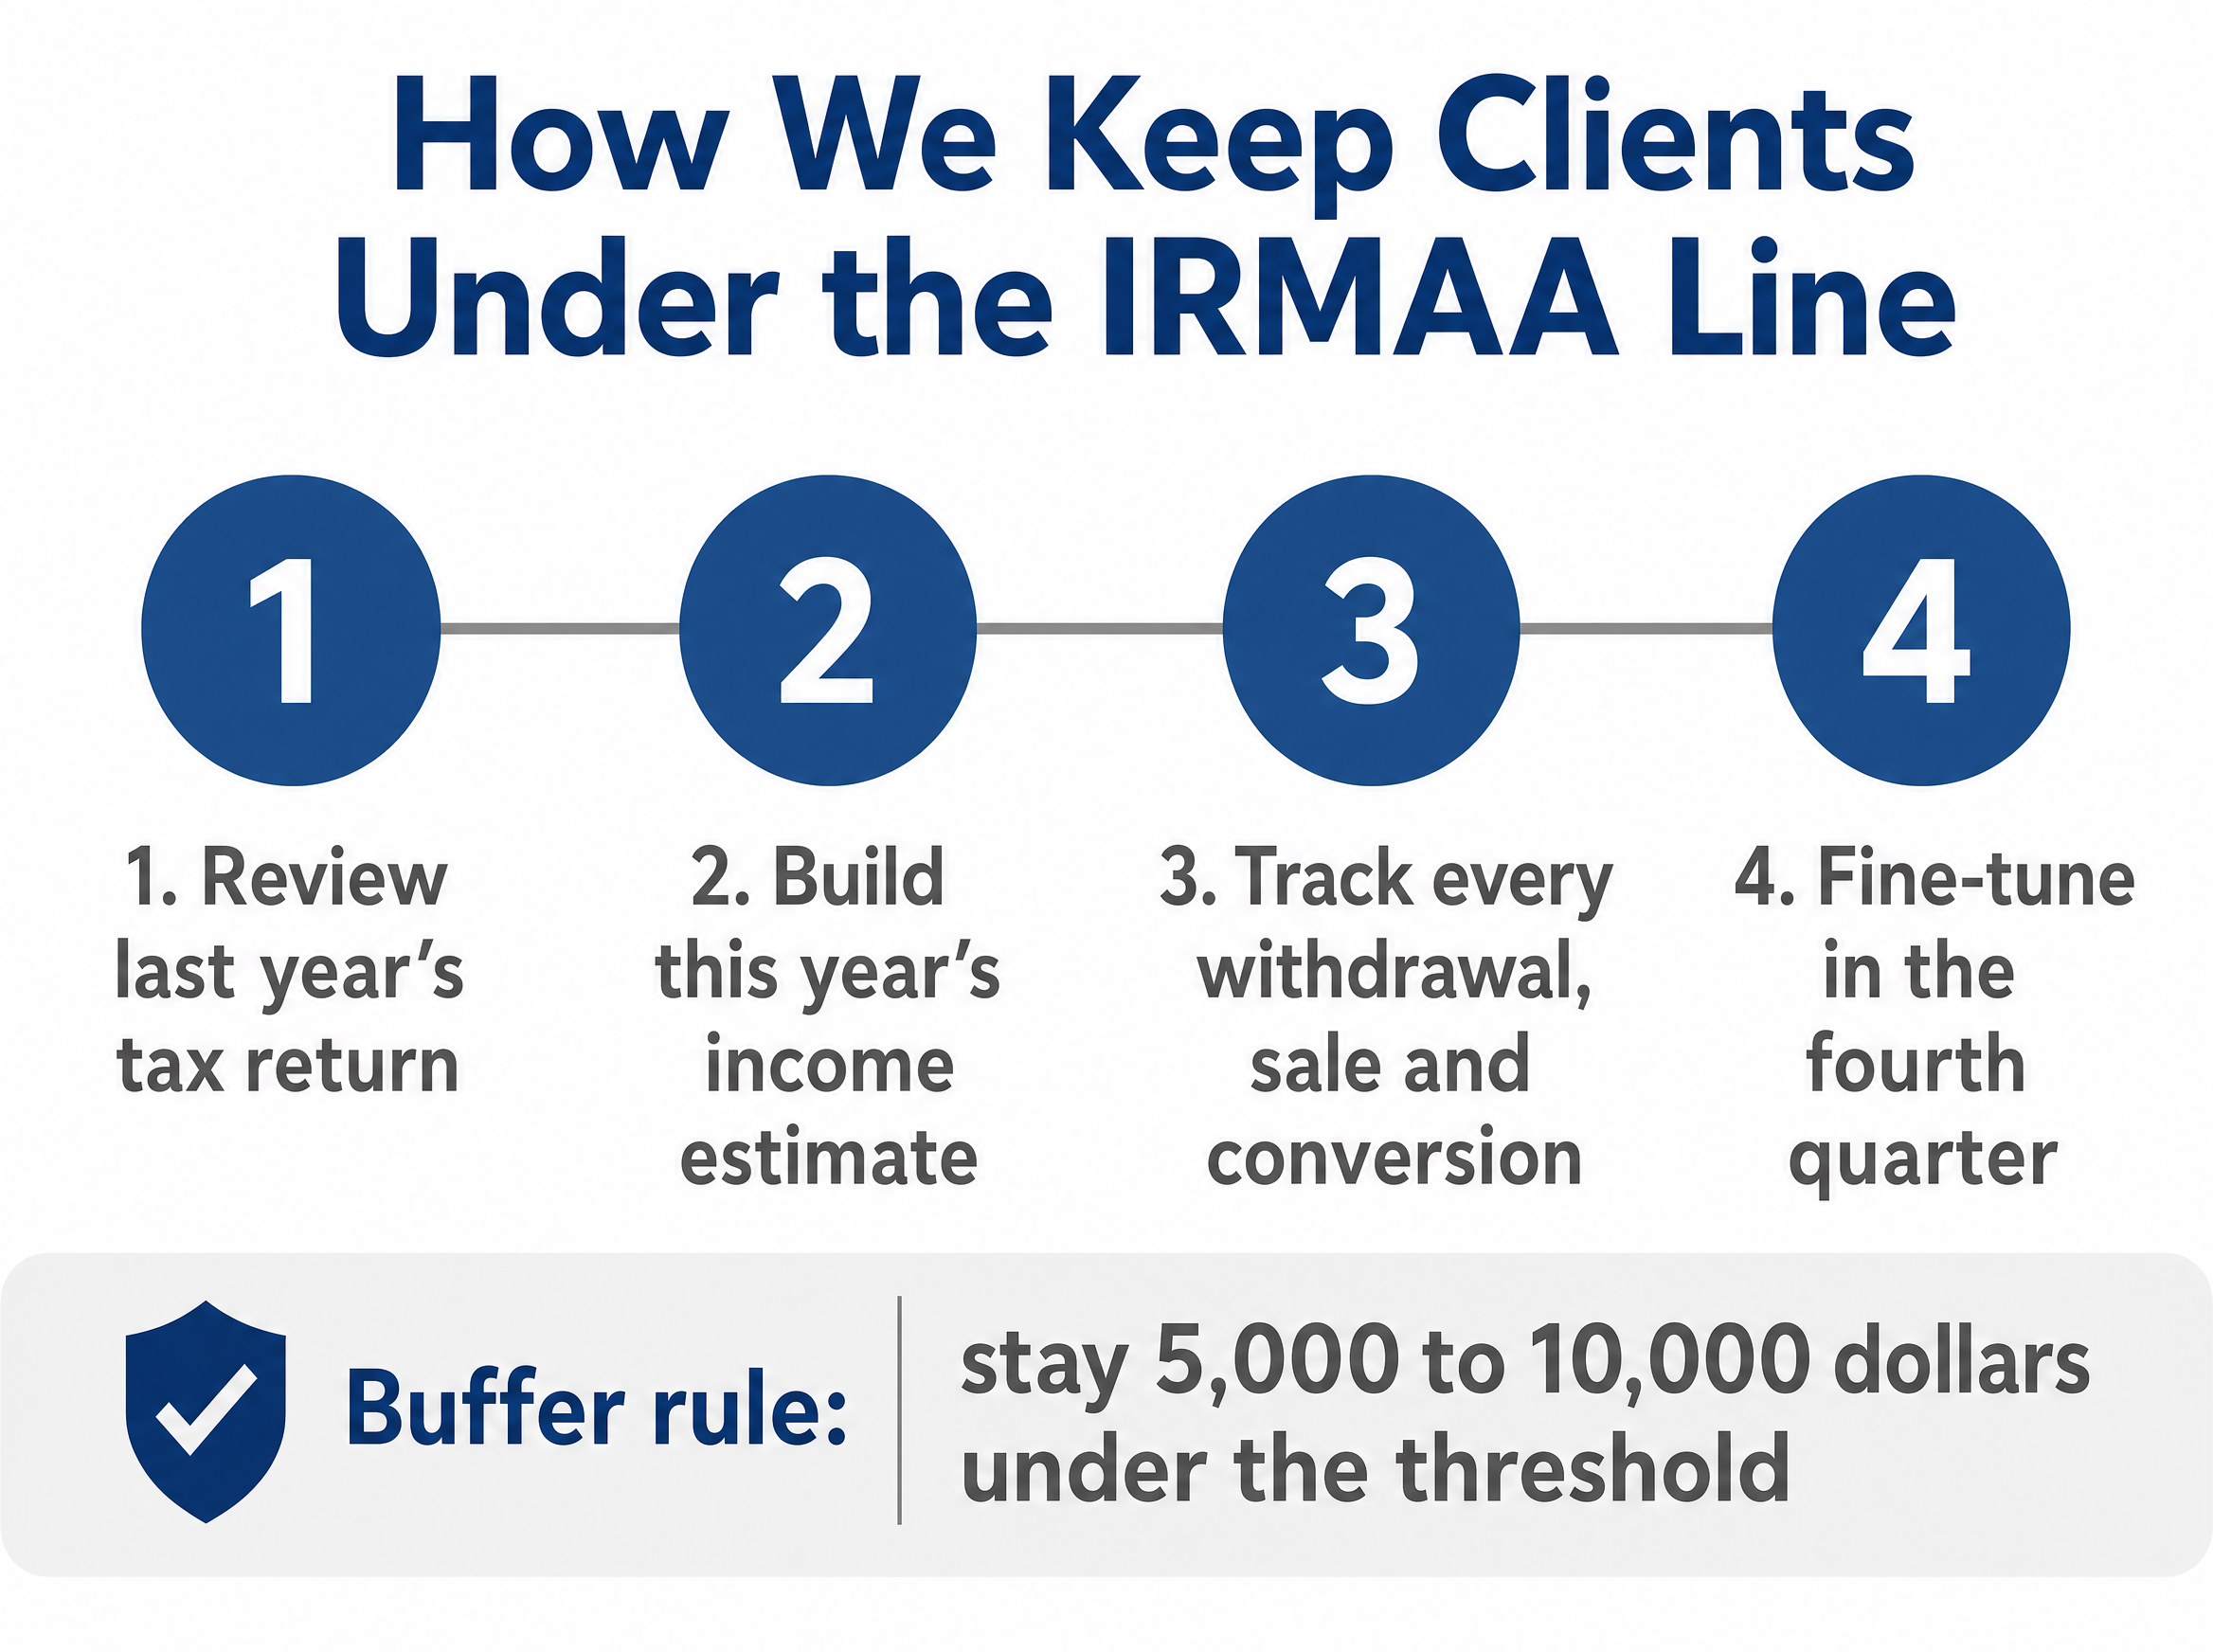
We do tax planning as a core service, and IRMAA is one of the main lines we watch. Here is the process, because I think most people assume this is more complicated than it is.
First, we review the prior year's tax return. That tells us where the income came from and how close to a threshold the client already sits.
Second, we build a tax planning estimate for the current year. Every known source of income goes in, and we lay it against the tax brackets and the IRMAA brackets side by side.
Third, we track it through the year. When a client wants to sell a property, take a big withdrawal, or convert to a Roth, we run it against that estimate before they act, not after.
Then in the fourth quarter we fine-tune the projection and make any last adjustments before December 31. After that the year is closed, and so is the Medicare number that goes with it.
The buffer rule
We do not plan to land exactly on the line. We leave at least $5,000 to $10,000 of room under whichever threshold applies.
And the reason for that is simple. A mutual fund can push out a capital gains distribution in December that you did not plan for, or a 1099 can come in higher than expected.
That buffer is what keeps a small surprise from turning into a $2,300 premium bill two years later.
If you would like to see how this works for your situation, our tax planning service is built around exactly this kind of year-round tracking.
Five Ways to Stay Under the IRMAA Brackets
You have done well to have this problem. High income in retirement is the goal, not the mistake.
Here is how we manage it.
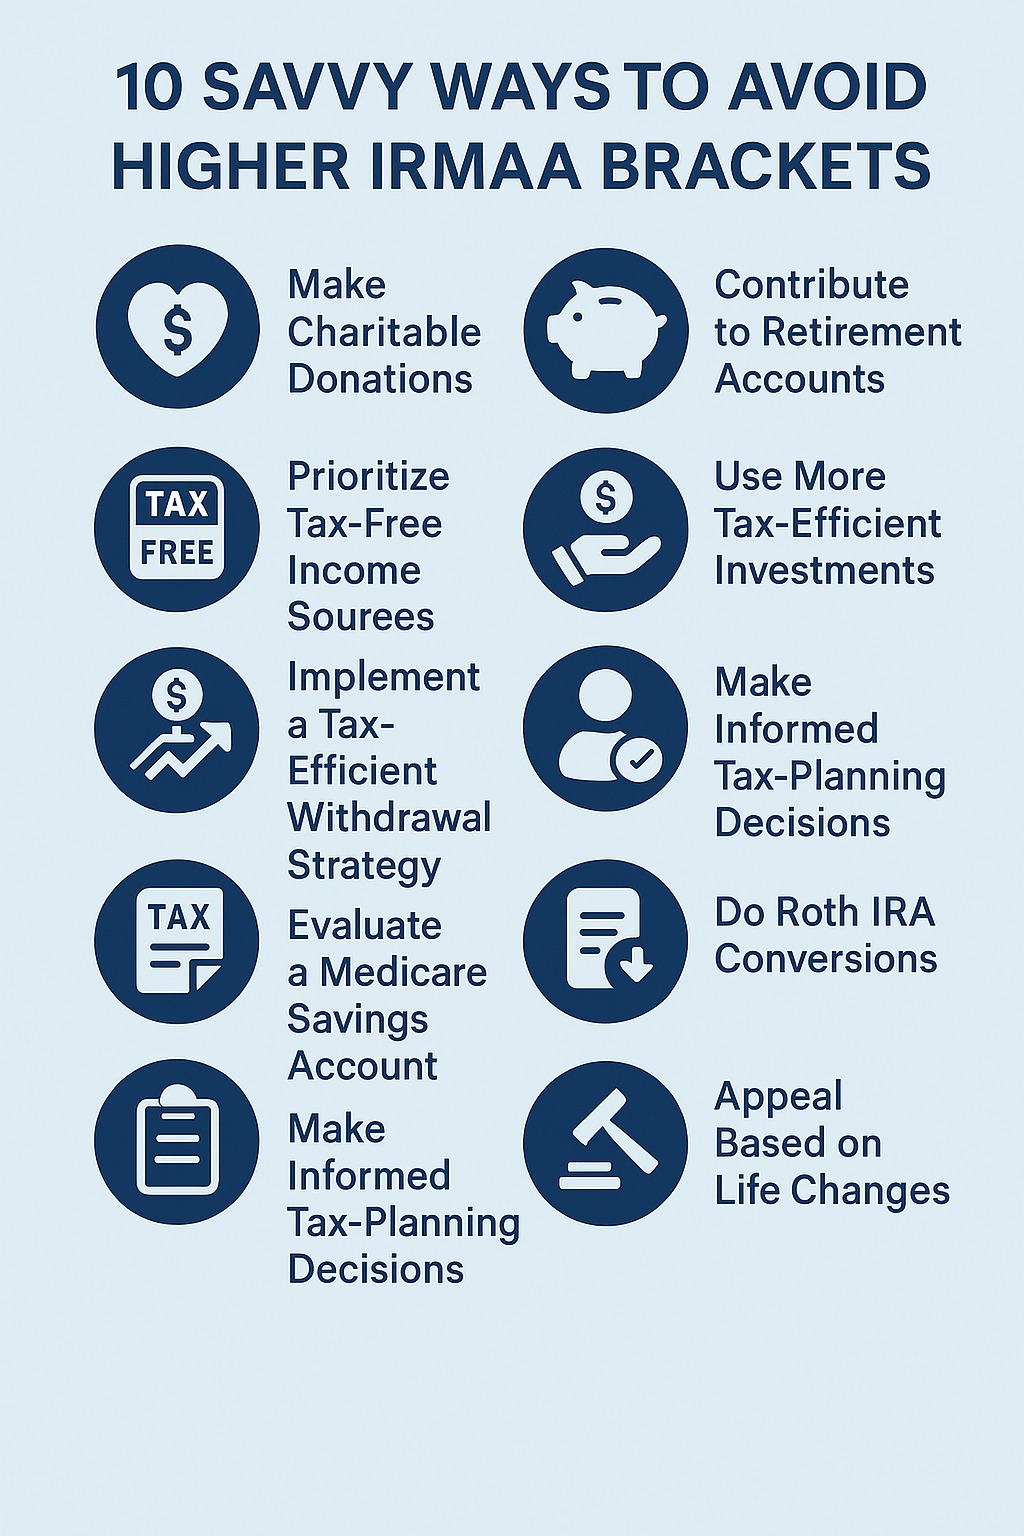
1. Convert to a Roth in the gap years, at the sweet spot
Your gap years are the window between retirement and RMD age. Income is at its lowest, and that is the best time to move money from a traditional IRA to a Roth.
Now, a conversion counts as income in the year you do it, so a conversion can trigger IRMAA on its own. The sweet spot is the amount that fills the tax bracket you want without crossing the Medicare line you do not.
We cover how to size that in our guide to Roth conversions.
2. Give from your IRA with a QCD checkbook
Once you turn 70 1/2, a qualified charitable distribution goes straight from your IRA to the charity and never touches your income. It counts toward your RMD and it never shows up in MAGI.
We set clients up with a QCD checkbook so the gift goes directly from the IRA. It removes the custodian back-and-forth and keeps the paper trail clean.
Our QCD guide walks through the rules.
3. Control the gains you did not choose
Actively managed funds trade inside the fund, and when they sell, you get a capital gains distribution whether you sold anything or not. We had a client with roughly $102,000 of long-term gains on a return, and a good chunk of it came from funds he never touched.
Passive index funds only create gains when you decide to sell. For someone already stacking Social Security, a pension, and RMDs, that control is the difference between staying under the line and crossing it.
4. Pull from the three tax buckets in the right order
Your money sits in three tax buckets: taxable, tax-deferred, and tax-free. Which bucket you pull from each year decides what shows up in MAGI.
A withdrawal from the Roth bucket adds nothing, and a withdrawal from the IRA bucket adds every dollar. Mixing them on purpose lets you cover your spending without crossing a threshold.
5. Time the big, one-time events
Selling a rental, exercising options, closing a business, or cashing a large inherited IRA can each blow through every bracket at once. Sometimes that is unavoidable.
But if you can split a sale across two tax years, or push a conversion into a year when other income is down, you can keep the surcharge to one year instead of two, or avoid it entirely. This is where having the projection built before you act pays for itself.
The Widow's Tax Trap and IRMAA
This is the part almost nobody writes about, and it hits our clients harder than any other.
When one spouse dies, the survivor goes from married filing jointly to single. The income tax brackets compress, and the IRMAA brackets get cut exactly in half.
But the income does not get cut in half. The survivor keeps the larger Social Security benefit, the pension, and every IRA, and the RMDs on all of it keep coming.
Here is what happened to one couple we work with. Together they had about $200,000 of MAGI and paid no surcharge at all.
When he passed, her income settled at around $150,000 because the RMDs did not go anywhere. As a single filer that put her in the third tier, and her Medicare premium went from $202.90 to $405.80 a month, plus $37.50 on Part D.
That is close to $2,900 a year, on top of the tax torpedo from filing single.
That is the widow's tax trap. It is a big part of why we push Roth conversions while both spouses are alive and the joint brackets are still available.
If You Got Hit and Your Income Has Dropped
IRMAA is based on a two-year-old return. If your life has changed since then, you can ask Social Security to use a more recent year instead.
Qualifying events include retirement or a reduction in work hours, the death of a spouse, marriage, divorce, loss of a pension, and loss of income-producing property. You file Form SSA-44 with proof of the event and an estimate of your new income.
A one-time IRA withdrawal or a Roth conversion is not a qualifying event. Social Security treats that as a choice, not a life change.
We wrote a separate step-by-step guide on how to appeal Medicare premium surcharges if you need to file one.
Frequently Asked Questions
What are the projected IRMAA brackets for 2028?
The 2028 brackets will be based on your 2026 income and will be announced in the fall of 2027. Current projections put the first threshold between $114,000 and $116,000 for single filers and $228,000 to $232,000 for married couples filing jointly, with the top tier staying at $500,000 single and $750,000 joint.
Is 2026 IRMAA based on 2024 income?
Yes, Medicare uses your modified adjusted gross income from the tax return you filed two years earlier. Your 2026 premium comes from your 2024 return, and your 2027 premium will come from your 2025 return.
What is the IRMAA threshold for married filing jointly in 2026?
The first surcharge tier for joint filers begins at $218,001 of 2024 MAGI, with the remaining lines at $274,001, $342,001, $410,001, and $750,000. Each spouse on Medicare pays the surcharge separately.
Does IRMAA reset every year?
Yes, Social Security recalculates it every year using the newest return on file. If your income drops below a threshold, the surcharge drops off two years later without you needing to do anything.
Does Social Security income count toward IRMAA?
Only the taxable portion, meaning the part of your Social Security benefit that is included in your adjusted gross income. The untaxed portion does not count, but tax-exempt municipal bond interest gets added back in.
Here's What Matters
- The 2026 IRMAA brackets start at $109,000 single and $218,000 joint, based on 2024 income
- IRMAA is a cliff. One dollar over a line costs the full tier surcharge for the whole year, per spouse
- Your 2026 income sets your 2028 premium, so this year's decisions are the ones that count
- The brackets below the top tier move with inflation; the $500,000 and $750,000 lines are frozen
- We plan with a $5,000 to $10,000 buffer under the line, tracked all year and tightened in the fourth quarter
- A surviving spouse keeps the income but loses half the bracket. Plan for the widow's tax trap while both of you are still filing jointly
Gudorf Financial Group is a fee-only, fiduciary retirement planning firm based in Dayton, Ohio. We serve clients locally and virtually nationwide.
Article References
- "Medicare Premiums: Rules for Higher-Income Beneficiaries." Social Security Administration. Accessed August 2026.
- "Medicare Costs." Medicare.gov. Accessed August 2026.
- "2026 2027 2028 Medicare IRMAA Premium MAGI Brackets." The Finance Buff. Accessed August 2026.
- "Form SSA-44: Medicare Income-Related Monthly Adjustment Amount, Life-Changing Event." Social Security Administration. Accessed August 2026.