

Ohio Capital Gains Tax in 2026: Rates, Real Estate, and How Retirees Pay Less
By Danny Gudorf | Founder, Gudorf Financial Group | Updated October 2026
So you have a stock position that has tripled, a rental you are ready to be done with, or a house that is worth four times what you paid. Before you sell, you want to know what the tax bill looks like.
The Ohio capital gains tax is the easy part. Ohio taxes the gain at a flat 2.75%, and that is the whole state rule.
The federal side is where the real money is. And for retirees, the bigger issue is how a gain stacks on top of Social Security, RMDs, and a pension in the year you sell.
Let me walk you through all three pieces: the Ohio rate, the federal rate, and what the gain does to the rest of your return.
How the Ohio Capital Gains Tax Works in 2026
Ohio does not have its own capital gains rate. A gain goes on your Ohio return as ordinary income, right next to your pension, your IRA withdrawals, and everything else.
Starting in 2026, Ohio moved to a flat income tax under the state budget bill, House Bill 96.
| Ohio taxable nonbusiness income | Ohio tax rate (2026) |
|---|---|
| $0 to $26,050 | 0% |
| Over $26,050 | 2.75% |
Here is what that means when you sell something:
- One rate for every gain. A $10,000 gain and a $500,000 gain are both taxed at 2.75% above the threshold.
- No short-term or long-term split. The federal government rewards you for holding more than a year. Ohio does not care how long you held it.
- The $26,050 zero bracket covers all of your Ohio income, not just the gain. If your pension and IRA withdrawals already fill it, the whole gain is taxed at 2.75%.
- Ohio does not tax Social Security. Your benefit does not use up any of that zero bracket.
Those last two points matter more than people expect. A retiree living mostly on Social Security in the early years can realize part of a gain with no Ohio tax at all.
Federal Capital Gains Tax Rates for 2026
So the federal rate depends on one thing first: how long you owned the asset.
Hold it more than one year and it is a long-term gain. Hold it one year or less and it is short-term.
Long-Term Capital Gains
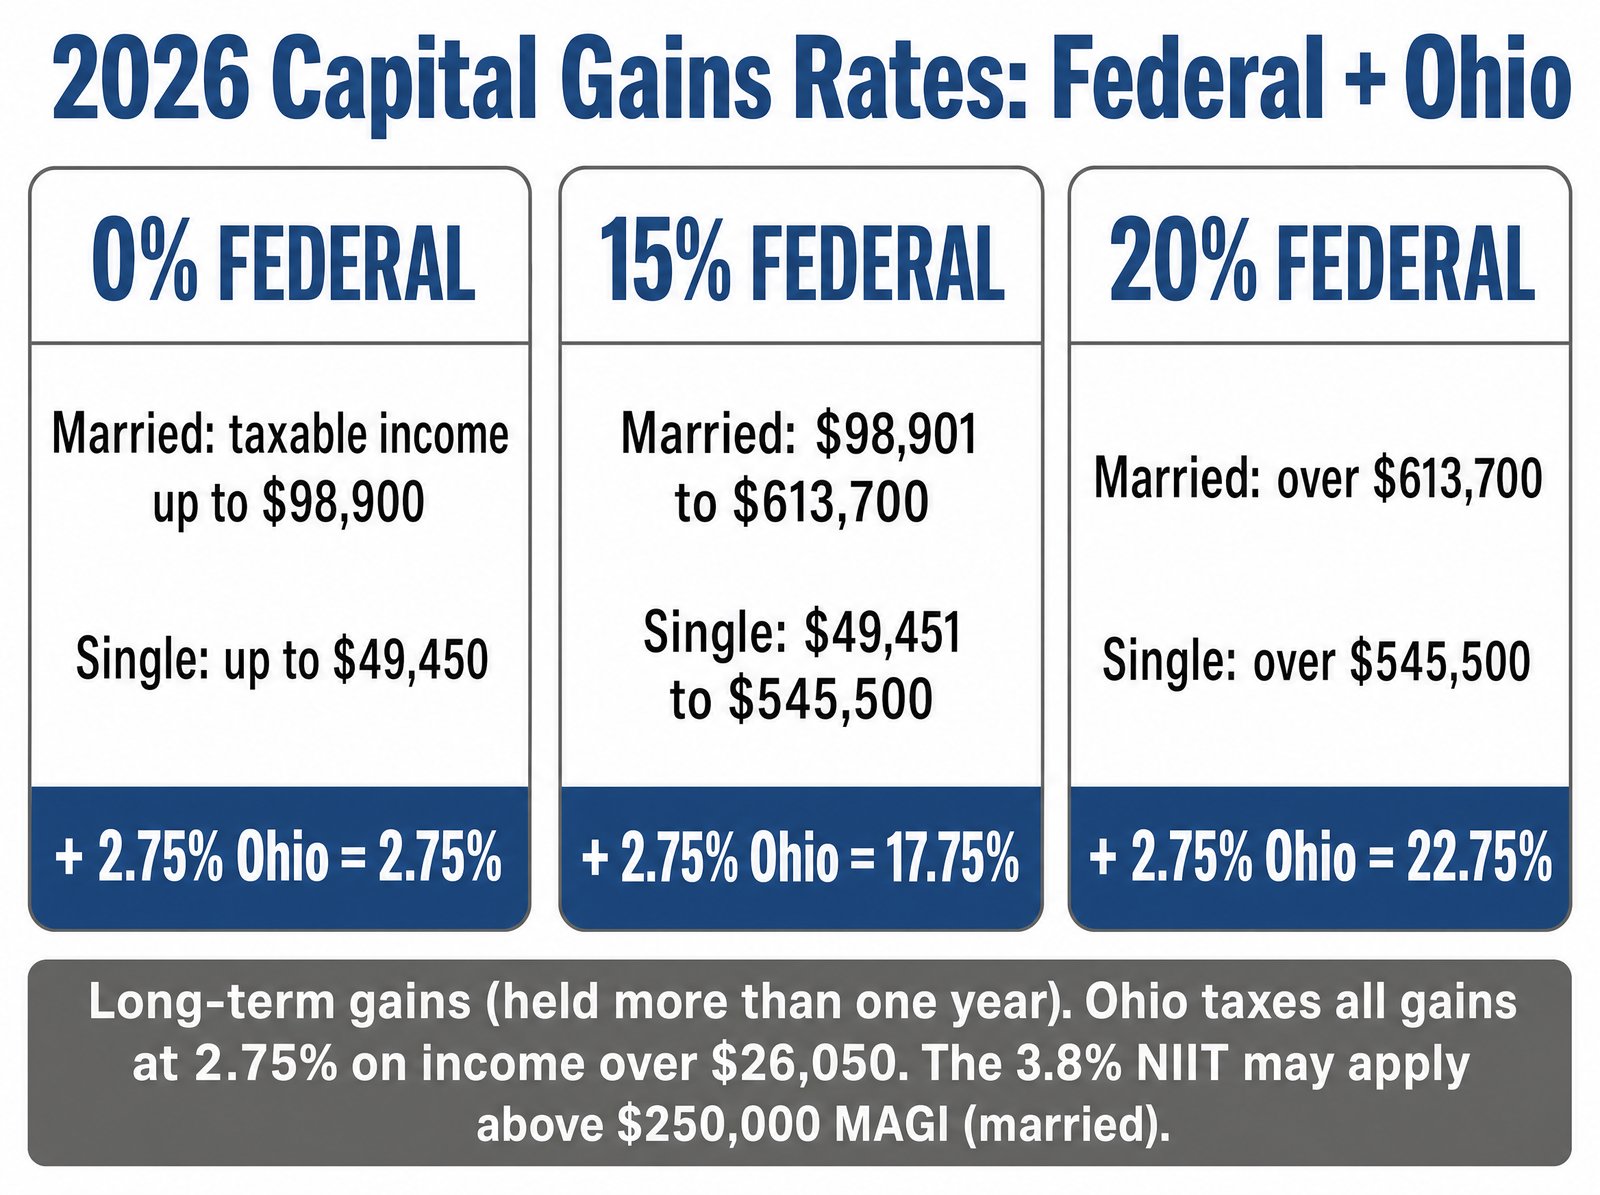
Long-term gains get their own lower rates. These are the 2026 thresholds from the IRS 2026 inflation adjustments, based on your total taxable income.
| Federal long-term rate | Married filing jointly | Single |
|---|---|---|
| 0% | Up to $98,900 | Up to $49,450 |
| 15% | $98,901 to $613,700 | $49,451 to $545,500 |
| 20% | Over $613,700 | Over $545,500 |
Short-Term Capital Gains
Short-term gains get no special treatment. They are taxed at your regular 2026 federal income tax brackets, the same as an IRA withdrawal.
| Federal rate | Married filing jointly | Single |
|---|---|---|
| 10% | Up to $24,800 | Up to $12,400 |
| 12% | $24,801 to $100,800 | $12,401 to $50,400 |
| 22% | $100,801 to $211,400 | $50,401 to $105,700 |
| 24% | $211,401 to $403,550 | $105,701 to $201,775 |
| 32% | $403,551 to $512,450 | $201,776 to $256,225 |
| 35% | $512,451 to $768,700 | $256,226 to $640,600 |
| 37% | Over $768,700 | Over $640,600 |
So check the purchase date before you sell. Waiting a few extra days to cross the one-year line can drop the federal rate from 22% or 24% down to 15%.
What You Actually Pay: Combined Ohio and Federal Rates
Now, the Ohio rate stacks directly on top of the federal rate. There is no credit or offset between the two.
| Your situation | Federal | Ohio | Combined |
|---|---|---|---|
| Long-term gain, taxable income under $98,900 (married) | 0% | 2.75% | 2.75% |
| Long-term gain, 15% federal bracket | 15% | 2.75% | 17.75% |
| Long-term gain, 15% bracket plus the 3.8% NIIT | 18.8% | 2.75% | 21.55% |
| Long-term gain, 20% bracket plus the 3.8% NIIT | 23.8% | 2.75% | 26.55% |
| Short-term gain, top 37% bracket plus the 3.8% NIIT | 40.8% | 2.75% | 43.55% |
That NIIT line is the Net Investment Income Tax, a 3.8% federal surtax on investment income. It applies once your modified adjusted gross income (MAGI) passes $250,000 for a married couple or $200,000 for a single filer.
A lot of our clients hit it in the one year they sell something big, even though they would never call themselves high earners. Let me show you how.
- A married couple has $180,000 of pension, RMD, and other income.
- They sell a stock position with a $100,000 long-term gain.
- Their MAGI is now $280,000, which is $30,000 over the line.
- The 3.8% applies to that $30,000, which comes to $1,140.
It is not a huge number on its own. But it lands on top of everything else the gain touches, which is where retirees get surprised.
Capital Gains Tax Over 65: Is There an Exemption for Seniors?
No. There is no age-based capital gains exemption at the federal level or in Ohio.
The old once-in-a-lifetime home sale break for people over 55 went away in 1997. It was replaced by the home sale exclusion everyone can use today, at any age.
What retirees do get is a set of rules that work in their favor if they plan around them:
- The 0% federal bracket. In a low-income year, a married couple can have up to $98,900 of taxable income and pay nothing federally on long-term gains.
- The home sale exclusion. Up to $250,000 of gain for a single filer and $500,000 for a married couple, covered below.
- The step-up in basis at death. Your heirs can sell appreciated assets with little or no gain.
- Ohio's treatment of Social Security. It never counts toward your Ohio income.
The point is that the break is not tied to your age. It is tied to your income in the year you sell, and that is something you can plan.
How a Capital Gain Stacks on Top of Your Retirement Income
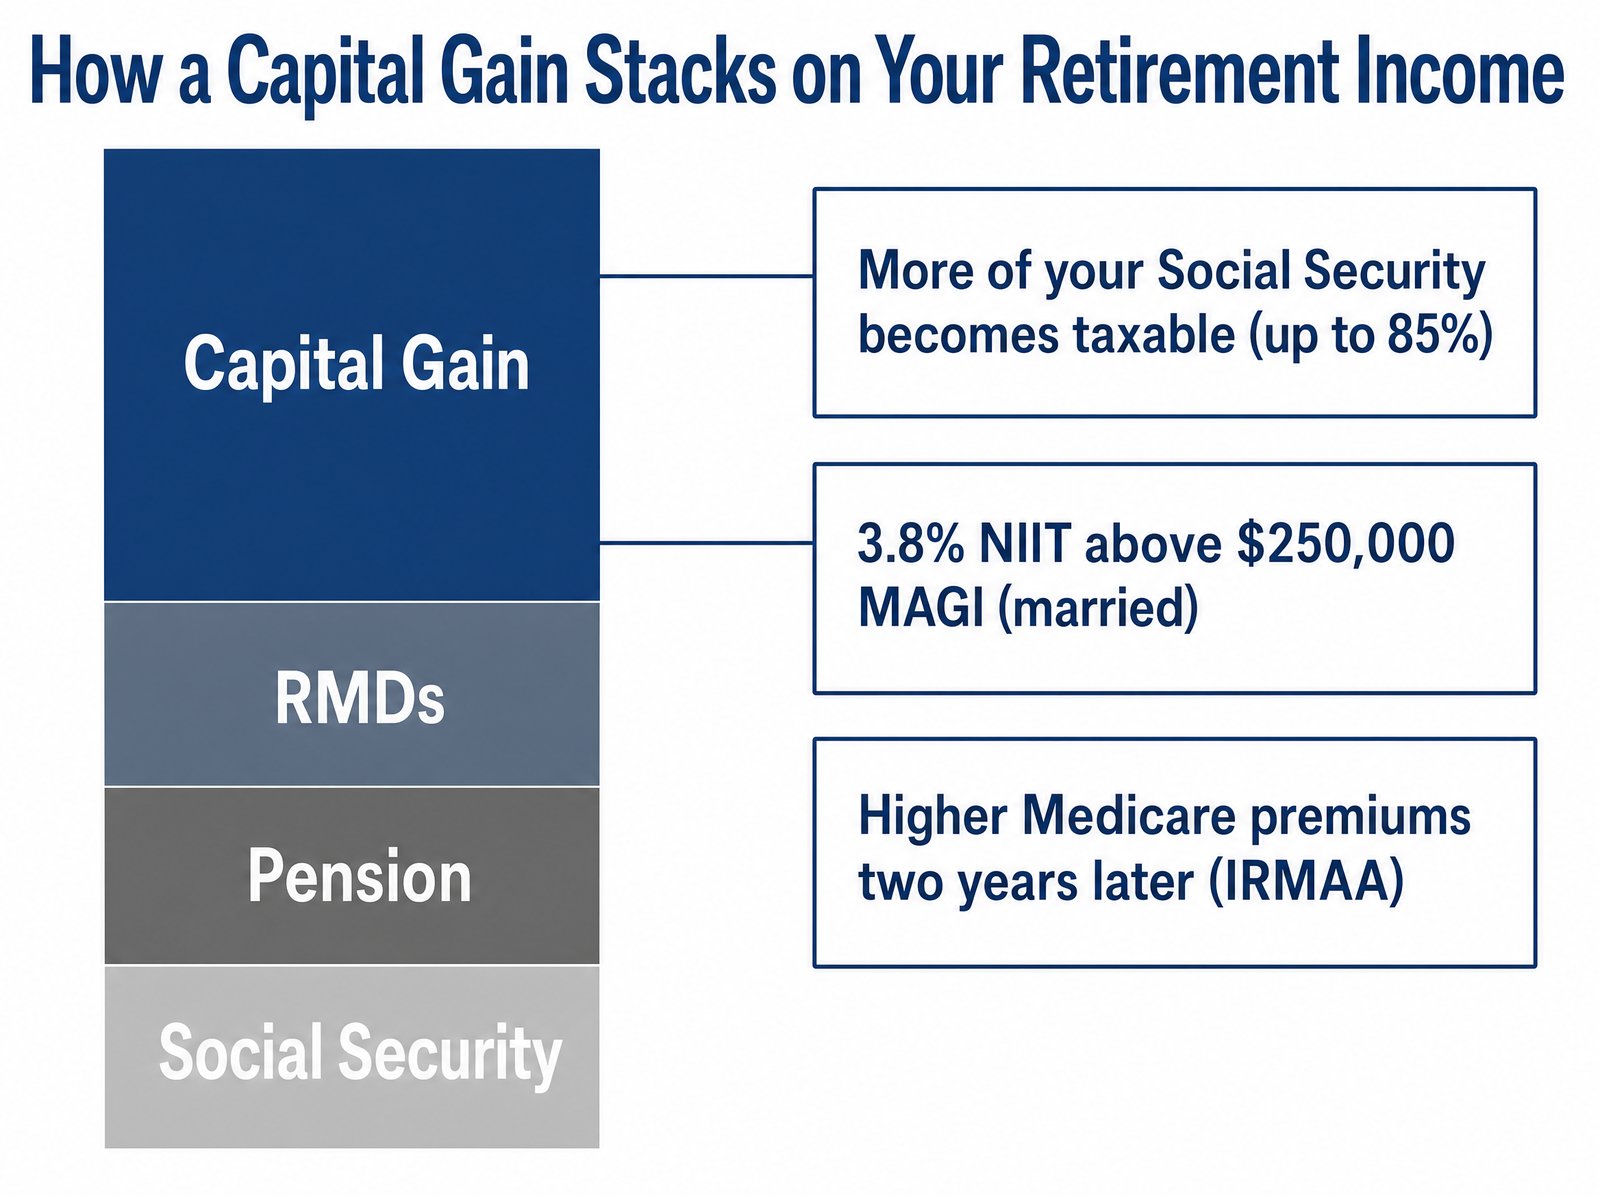
Here's the thing. A gain never gets taxed in a vacuum.
It sits on top of your Social Security, your pension, and your RMDs. So when we look at a sale for a client, there are three things we check.
- Social Security taxation. A gain raises the income the IRS uses to decide how much of your benefit is taxable, up to 85% of it federally. It can also shrink or wipe out the $6,000 senior deduction, which starts phasing out at $150,000 of MAGI for a couple.
- The NIIT. As shown above, a big gain can push MAGI past $250,000 for the first time.
- Medicare IRMAA. Medicare looks back two years at your income, so a gain you take in 2026 sets your premiums in 2028. The 2026 surcharges start at $218,000 of MAGI for a couple and $109,000 for a single filer, and those lines adjust each year. We cover the tiers in our guide to Medicare IRMAA brackets.
We see this all the time. Say you've got a couple, both 68, living on Social Security, a pension, and IRA withdrawals, and they realize about $102,000 of long-term capital gains in 2026.
They may have sold some of that on purpose. A good share of it was pushed out by actively managed funds, which trade inside the fund and pass the gains through at year end.
That gain wipes out most of their senior deduction, pushes them into a higher bracket, and trips the IRMAA threshold for 2028. They end up paying more for Medicare because a fund manager decided to trade.
Passive index funds give us far more control over when gains show up. For a retiree already stacking Social Security, a pension, and RMDs, that control matters.
We go deeper on this in could capital gains push you into a higher tax bracket.
Capital Gains Tax on Ohio Real Estate
For a lot of our clients, real estate is the biggest gain they will ever take. Ohio follows the federal rules on all of it, because your Ohio return starts from your federal adjusted gross income.
Selling Your Home
The IRS home sale exclusion lets you skip tax on up to $250,000 of gain as a single filer, or $500,000 as a married couple. You need to have owned the home and lived in it for at least two of the five years before the sale.
Whatever is excluded federally is also excluded in Ohio. Anything past the limit is taxable, like this:
- A married couple bought their home 30 years ago for $150,000.
- They sell it in 2026 for $750,000, a $600,000 gain.
- The first $500,000 is excluded.
- The remaining $100,000 is a long-term gain. At 15% federal plus 2.75% Ohio, that is about $17,750.
Keep your records for capital improvements, like a new roof, an addition, or a kitchen remodel. Those raise your cost basis and shrink the taxable gain.
Rental Property and Depreciation Recapture
Rentals are more complicated, and the piece people miss is depreciation recapture. Every year you owned the rental, you deducted depreciation, and when you sell, the IRS taxes that depreciation back at a federal rate of up to 25%.
Here is a simplified example.
| Piece of the sale | Amount | How it is taxed |
|---|---|---|
| Purchase price | $300,000 | Original cost basis |
| Depreciation taken over the years | $80,000 | Lowers your basis to $220,000 |
| Sale price | $500,000 | Total gain of $280,000 |
| Depreciation recapture | $80,000 | Federal rate up to 25% |
| Remaining long-term gain | $200,000 | Federal 15% or 20% |
| Ohio tax | $280,000 | 2.75% on the full gain, about $7,700 |
At the 15% bracket, that sale can run $57,700 or more before the NIIT even enters the picture. Run the numbers before you list the property, not after it closes.
Inherited Property and the Step-Up in Basis
When you inherit property, your cost basis resets to its value on the date of death. That is the step-up in basis.
Say your parents bought a rental for $100,000 and it was worth $600,000 when they passed. Your basis is $600,000, so if you sell it for $610,000, your taxable gain is only $10,000.
1031 Exchanges
A 1031 exchange lets you sell an investment property and roll the gain into a replacement property instead of paying tax now. The tax is deferred, not erased.
The timing rules are strict:
- 45 days from the sale to identify the replacement property.
- 180 days from the sale to close on it.
- Miss either deadline and the full gain is taxable that year.
For a retiree, a 1031 can make sense if you plan to hold the new property until death, since your heirs get the step-up. If you want out of being a landlord for good, it does not solve that problem.
Selling a Business in Ohio: The New 2026 Deduction
Ohio added two new capital gains deductions starting in 2026. The one that matters most for retirees covers gains from selling your ownership interest in an Ohio business, under Ohio Revised Code section 5747.79.
It comes with conditions:
- Ohio headquarters. The business has to be headquartered and organized in Ohio for the five years before the sale.
- Material participation. You need to have actively worked in the business for the five years before the sale.
- Stock or ownership sale only. It does not apply to an asset sale.
- A payroll cap. The deduction is the smaller of your gain or your share of the Ohio payroll the business paid over those five years, not counting pay to you or close family.
Now, how the deal is structured decides whether you qualify. So get your CPA involved before you sign a letter of intent, not at closing.
How to Reduce Capital Gains Tax in Ohio in Retirement
It can get a lot more complicated than this. But in its simplest form, there are three places we look to lower the tax on a gain.
One: When You Sell
- Use your gap years. Your gap years are the window between retiring and when RMDs start. The paycheck has stopped and RMDs have not started, so there can be room to sell at the 0% federal rate.
- Spread a big sale over two tax years. Selling half in December and half in January can keep each year under a threshold.
- Use an installment sale for a business or property. Getting paid over several years spreads the gain across several tax returns.
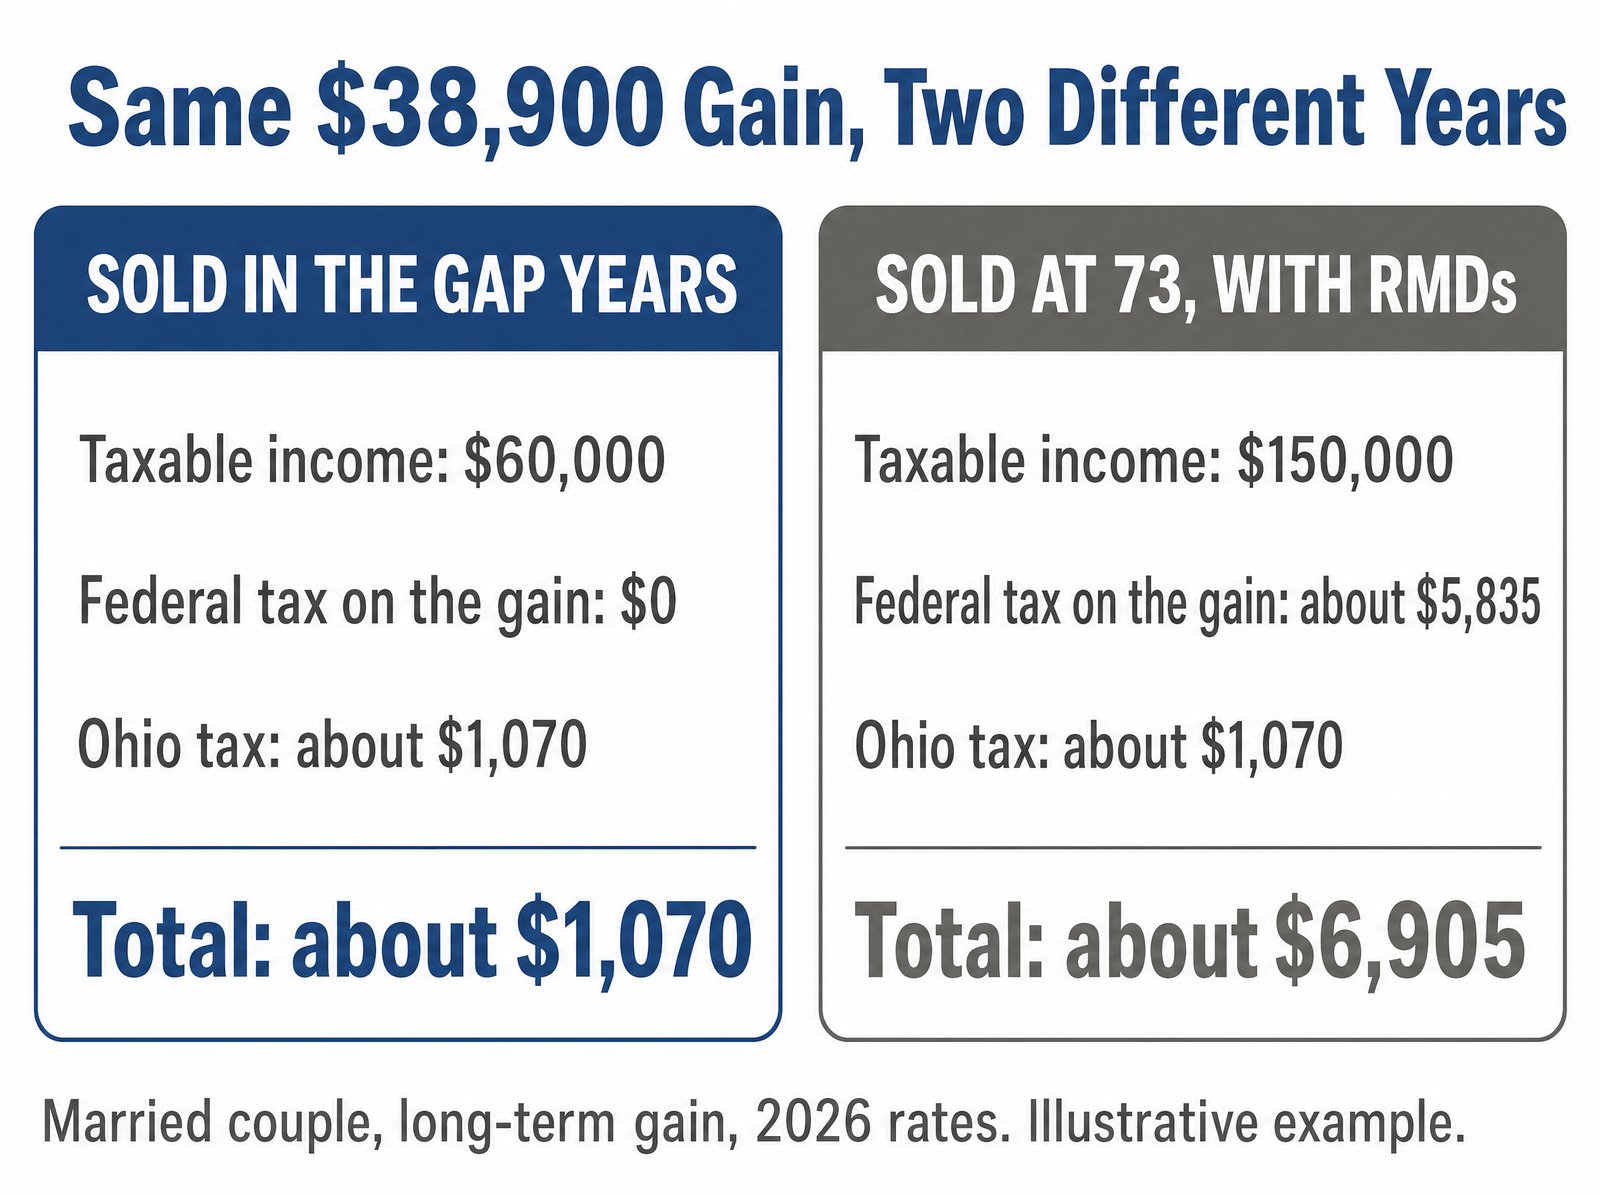
Let me show you what timing can do. A married couple in their gap years has $60,000 of taxable income, which leaves $38,900 of room under the 0% line.
- Sold now: $38,900 of gain, $0 federal, about $1,070 to Ohio.
- Sold at 73, with RMDs pushing taxable income to $150,000: the same gain costs about $5,835 federally plus the same $1,070 to Ohio.
We are making a lot of assumptions here, and your numbers will be different. But the gap is real, and it is the kind of thing our tax planning process looks for every year.
Two: What You Sell and Where It Lives
- Harvest losses. Losses offset gains dollar for dollar. If losses exceed gains, up to $3,000 a year comes off your other income, and the rest carries forward.
- Pay attention to asset location. Asset allocation is what you own. Asset location is which account it lives in, and funds that throw off gains belong in an IRA, not a brokerage account.
- Favor low-cost index funds in taxable accounts. They rarely push out year-end capital gains distributions you did not ask for.
Three: What You Do With It Instead of Selling
- Donate appreciated shares. Give the stock directly to charity and you skip the gain entirely. A donor-advised fund lets you do it in one year and grant the money over time.
- Hold it until death. If you will never need the money, your heirs get the step-up and the gain disappears.
- Know which bucket you are leaving behind. We think in terms of the three tax buckets: taxable, tax-deferred, and tax-free. A brokerage account gets a step-up at death, but an IRA does not, so your heirs pay ordinary income tax on every IRA dollar they take out.
Not every strategy fits every family. If you are going to spend the money in the next few years anyway, holding out for a step-up makes no sense, and we would tell you that.
Ohio Capital Gains Tax FAQs
Does Ohio have a capital gains tax?
Ohio does not have a separate capital gains tax. Gains are taxed as regular income on your Ohio return.
In 2026, that is a flat 2.75% on Ohio income over $26,050.
What is the Ohio capital gains tax rate for 2026?
The rate is 2.75% on Ohio taxable income over $26,050, and 0% below that. Ohio treats short-term and long-term gains the same.
Your federal rate is separate and depends on your total income.
Do seniors over 65 pay capital gains tax in Ohio?
Yes. There is no age exemption in Ohio or at the federal level.
What helps retirees is income timing. In a lower-income year, a married couple can have up to $98,900 of taxable income and pay 0% federal tax on long-term gains, though Ohio still applies its 2.75%.
Do I pay Ohio tax when I sell my house?
Not on the part covered by the federal home sale exclusion, which is up to $250,000 for a single filer and $500,000 for a married couple. You need to have owned and lived in the home for two of the last five years.
Any gain above the exclusion is taxed by both the IRS and Ohio.
How is inherited property taxed in Ohio when I sell it?
Your cost basis steps up to the property's value on the date of death. You only pay tax on growth after that date, at 2.75% in Ohio plus the federal rate.
Ohio has no inheritance tax, so there is no separate state tax just for inheriting.
Here's What Matters
- Ohio taxes capital gains as regular income, at a flat 2.75% above $26,050 in 2026, with no short-term or long-term split.
- Federal long-term rates are 0%, 15%, or 20%. For a married couple, the 0% rate covers taxable income up to $98,900.
- Most retirees in the 15% bracket pay a combined 17.75%. The 3.8% NIIT can push that to 21.55% or higher.
- A gain can make more of your Social Security taxable, trigger the NIIT, and raise your Medicare premiums two years later.
- There is no age exemption. The breaks that matter are the home sale exclusion, the step-up at death, and selling in low-income years.
- Ohio's new 2026 business sale deduction has strict rules. Plan the structure before you sign anything.
Gudorf Financial Group is a fee-only, fiduciary retirement planning firm based in Dayton, Ohio. We serve clients locally and virtually nationwide.
Article References
- "Ohio budget bill makes significant tax changes for a variety of taxpayers." Plante Moran. July 2025.
- "Revenue Procedure 2025-32." Internal Revenue Service. October 2025.
- "IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill." Internal Revenue Service. October 2025.
- "Topic No. 559, Net Investment Income Tax." Internal Revenue Service. Accessed October 2026.
- "Check your eligibility for the new enhanced deduction for seniors." Internal Revenue Service. Accessed October 2026.
- "2026 Medicare Parts A & B Premiums and Deductibles." Centers for Medicare & Medicaid Services. November 2025.
- "Topic No. 701, Sale of Your Home." Internal Revenue Service. Accessed October 2026.
- "Section 5747.79, Ohio Revised Code." Ohio Laws. Accessed October 2026.
- "Topic No. 409, Capital Gains and Losses." Internal Revenue Service. Accessed October 2026.