

How to Lower Your AGI in Retirement: 7 Moves That Actually Work After 65
By Danny Gudorf | Founder, Gudorf Financial Group | Updated October 2026
Search "how to lower AGI" and you get the same list every time. Max out your 401(k), fund an HSA, deduct your student loan interest.
That list is written for a 40-year-old with a paycheck. If you are retired, you cannot do most of it, and the moves that do work are not on it.
So this post is the retiree version. Here is what actually counts in your adjusted gross income once you stop working, why the number matters more in 2026 than it did two years ago, and the seven levers we use with clients to bring it down.
Why Your AGI Matters More in 2026
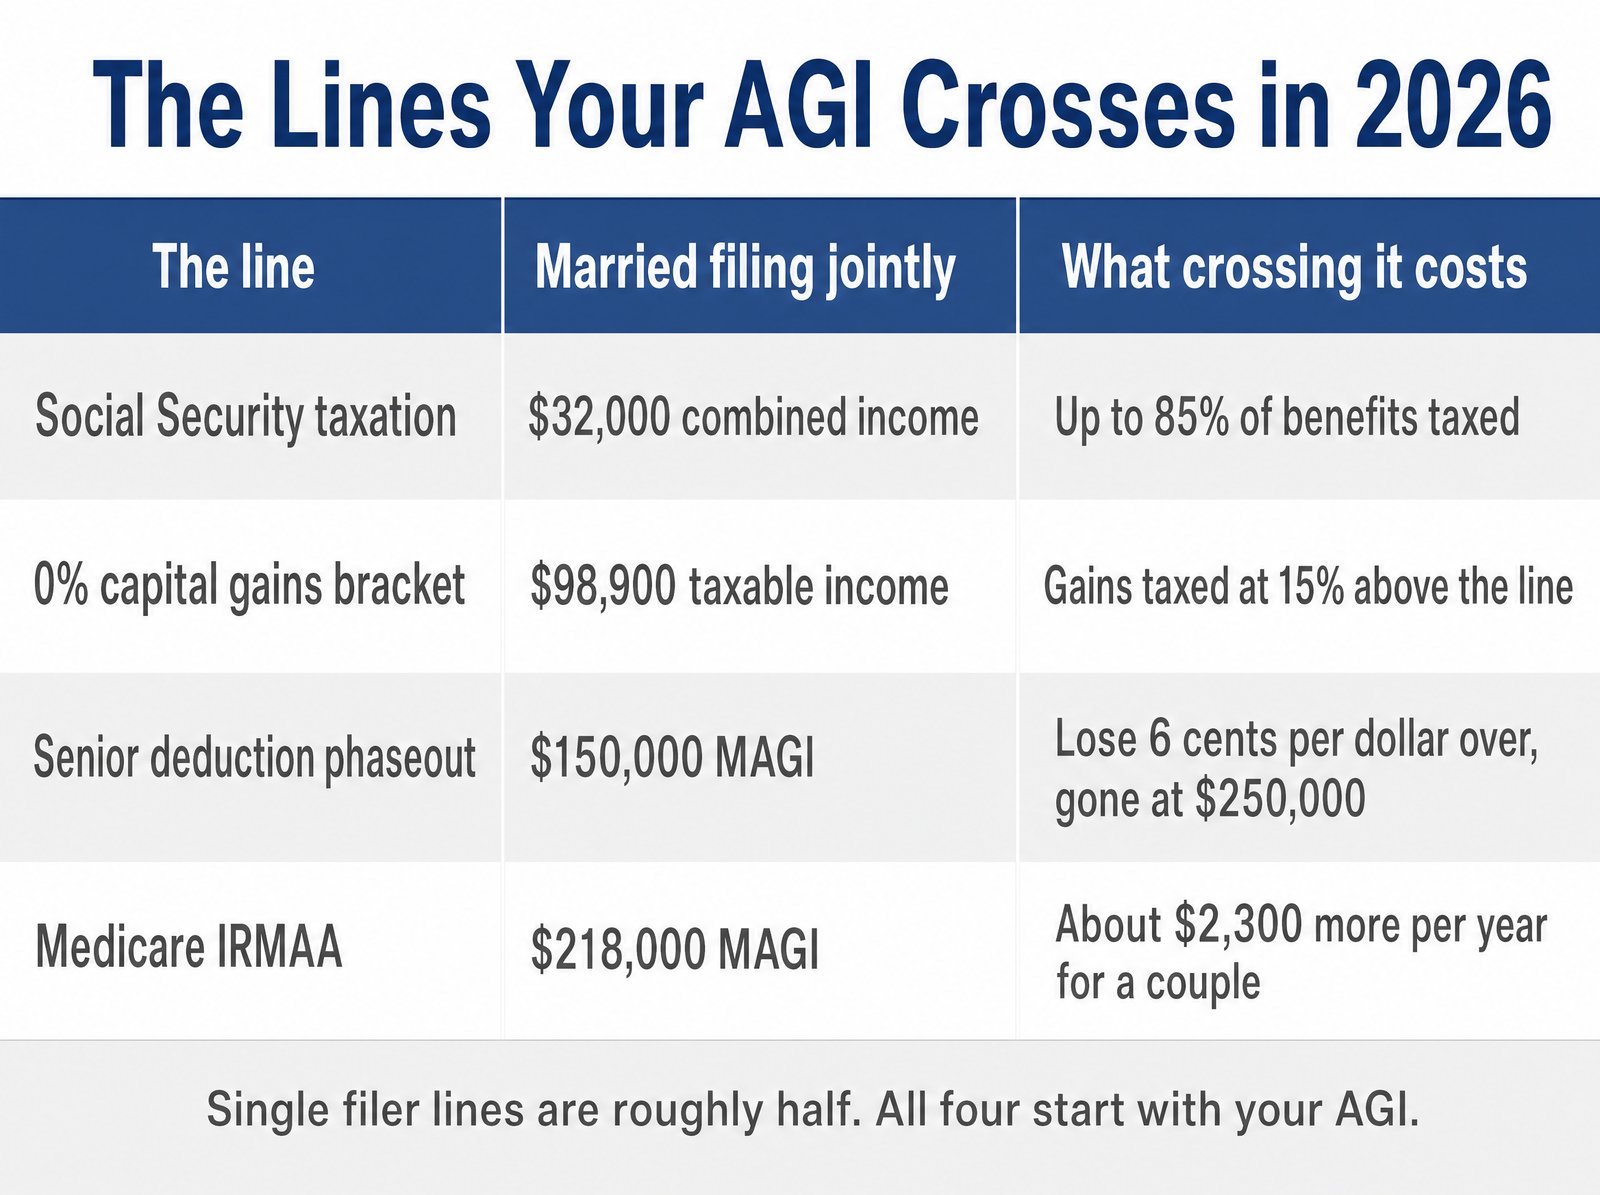
AGI has always set your tax bracket and how much of your Social Security gets taxed. What changed is how many lines now sit on top of it.
| The line | Where it sits in 2026 | What crossing it costs |
|---|---|---|
| Social Security taxation | $32,000 combined income, married; $25,000 single | Up to 85% of your benefit becomes taxable above $44,000 / $34,000 |
| 0% long-term capital gains | $98,900 taxable income, married; $49,450 single | Gains above the line are taxed at 15% instead of 0% |
| Senior deduction phaseout | Starts at $150,000 MAGI, married; $75,000 single | Each spouse's $6,000 drops 6 cents for every dollar over; gone at $250,000 / $175,000 |
| Medicare IRMAA | $218,000 MAGI, married; $109,000 single | About $2,300 a year in extra premiums for a couple, and it climbs from there |
Now, those are four different definitions of income. Combined income, taxable income, and modified AGI are each a little different from plain AGI.
But every one of them starts with AGI. Bring AGI down and every line above it gets easier.
What Counts Toward AGI in Retirement (and What Does Not)
Here is the part most people get wrong. They think of income as the money that hits the checking account, and that is not how the IRS sees it.
Counts toward AGI:
- Traditional IRA and 401(k) withdrawals, including RMDs
- Roth conversions, in the year you convert
- Pension payments
- The taxable portion of Social Security (up to 85%)
- Interest, dividends, and capital gains in your taxable account
- Capital gains distributions from mutual funds, even if you sold nothing
- Rental income and part-time work
Does not count toward AGI:
- Roth IRA withdrawals, once the account is five years old and you are 59 1/2
- Qualified charitable distributions from your IRA
- Withdrawals of your own principal from a taxable account
- The untaxed portion of Social Security
- Cash sitting in your war chest
Think about it this way. Two couples can spend the exact same $120,000 a year and show up with AGIs of $130,000 and $60,000.
The difference is which bucket the money came out of.
Which Line Are You Managing To?
Before you pull any lever, you have to know which line matters for you this year. Our clients come in with very different goals, and the right move depends on the goal.
- Under 65 and buying health insurance on the exchange. The enhanced ACA subsidies expired at the end of 2025, so the cliff is back. Go one dollar over 400% of the poverty line, about $85,000 for a couple in 2026, and the entire premium credit disappears. For these clients, AGI is the whole game until Medicare starts.
- Sitting on a large taxable account. These clients want to harvest gains at 0%, which means keeping taxable income under $98,900 as a couple. Every IRA dollar they pull uses up room they wanted for gains.
- Sitting on a large IRA. These clients want the opposite. They want to fill up the low brackets with Roth conversions during the gap years, which pushes AGI up on purpose now to bring it down for the next 25 years.
- Age 65 and over. The $6,000 senior deduction starts phasing out at $150,000 of MAGI for a couple, and IRMAA starts at $218,000. Both are worth watching, and I will get to how we weigh them against conversions below.
The point is, there is no single "right" AGI. There is the right AGI for what you are optimizing for this year.
Seven Ways to Lower Your AGI in Retirement
You have done well to have this problem. These are the levers that work after the paycheck stops.
1. Pull from the three tax buckets in the right order
Your money sits in three tax buckets: taxable, tax-deferred, and tax-free. Which bucket funds your retirement paycheck each year decides most of your AGI.
A dollar from the IRA adds a dollar to AGI. A dollar of principal from the brokerage account adds nothing, and neither does a dollar from the Roth.
So when a client needs $10,000 more for a trip or a roof, we do not just take it from the IRA. We look at where they sit against the lines above and pull from whichever bucket keeps them under the one that matters.
2. Give from your IRA with a QCD checkbook
This is the one charitable move that lowers AGI directly. Once you are 70 1/2, a qualified charitable distribution goes straight from your IRA to the charity, counts toward your RMD, and never shows up in AGI at all.
A cash gift you deduct on Schedule A does not do that. It lowers taxable income, but AGI is already set by then, so it does nothing for the senior deduction, IRMAA, or Social Security taxation.
We set clients up with a QCD checkbook so gifts go straight from the IRA without the custodian back-and-forth. The 2026 limit is $111,000 per person, and our QCD guide covers the rules.
3. Convert to a Roth in the gap years, at the sweet spot
Here is the lever that looks backwards. A Roth conversion raises your AGI in the year you do it.
But your gap years, the window between retirement and RMD age, are the lowest-income years you will ever have again. Fill the 12% or 22% bracket now and every dollar you convert comes out of the AGI you would have had at 75, 80, and 85, when the RMD factor keeps climbing.
The sweet spot is the amount that fills the bracket you want without crossing a line you care about this year. Convert too little and the RMDs catch you later; convert too much and you pay 24% today to avoid 22% later.
We walk through the sizing in our guide to Roth conversions.
4. Put the right investments in the right accounts
Asset location, not asset allocation. Bonds and REITs throw off ordinary income every year, so they belong inside the IRA where nothing hits your return until you take it out.
Broad index funds belong in the taxable account. They pay qualified dividends, they rarely push out gains, and you decide when to sell.
Get this backwards and a taxable account full of bond funds and REITs adds thousands to AGI every year whether you spend it or not.
5. Stop the gains you did not choose
Actively managed mutual funds trade inside the fund, and when the manager sells, you get a capital gains distribution in December. It lands on your return whether you sold anything or not.
Say you've got a couple, both 68, living on Social Security, a pension, and IRA withdrawals. Their return shows about $102,000 of long-term gains, and a good share of it was pushed out by funds they never touched.
That one line item trips IRMAA, wipes out most of their $12,000 senior deduction, and pushes them into a higher bracket.
Passive index funds only create gains when you decide to sell. For a retiree already stacking Social Security, a pension, and RMDs, that control is worth more than any deduction on the generic list.
6. Harvest losses in bad years and gains in low-income years
When the market drops, selling a losing position and buying something similar lets you deduct up to $3,000 of net losses against ordinary income and carry the rest forward. That lowers AGI directly.
The reverse works too. In a year when income is low, sell appreciated positions up to the top of the 0% capital gains bracket, then buy them right back at the higher cost basis.
You reset the gain to zero and paid nothing for it.
Now, harvested gains do add to AGI in that year. So this one has to be checked against the Social Security and subsidy lines before you do it.
7. Keep the big one-time events from stacking
Selling a rental, closing a business, cashing an inherited IRA, and starting Social Security are each fine on their own. Put two of them in the same tax year and you can blow through every line in the table at once.
If you can split a sale across December and January, or delay Social Security a year while you finish converting, you keep each event in its own year. This is where having the projection built before you act, not after, pays for itself.
What Stops Working Once You Retire
I want to be honest about the generic list, because most of it goes away the day the paycheck stops.
- 401(k) and IRA contributions need earned income. If you are still working part time, the 2026 401(k) and IRA limits are $24,500 plus an $8,000 catch-up for the 401(k) and $7,500 plus $1,100 for an IRA. If you are not, this lever is gone.
- HSA contributions stop the month you enroll in Medicare. Before 65 they are still one of the best deductions available, $8,750 for a family in 2026 plus a $1,000 catch-up.
- Student loan interest, educator expenses, alimony apply to almost none of our clients.
That is why the retiree list above looks nothing like the one you find everywhere else.
Two Couples, Two Different Answers
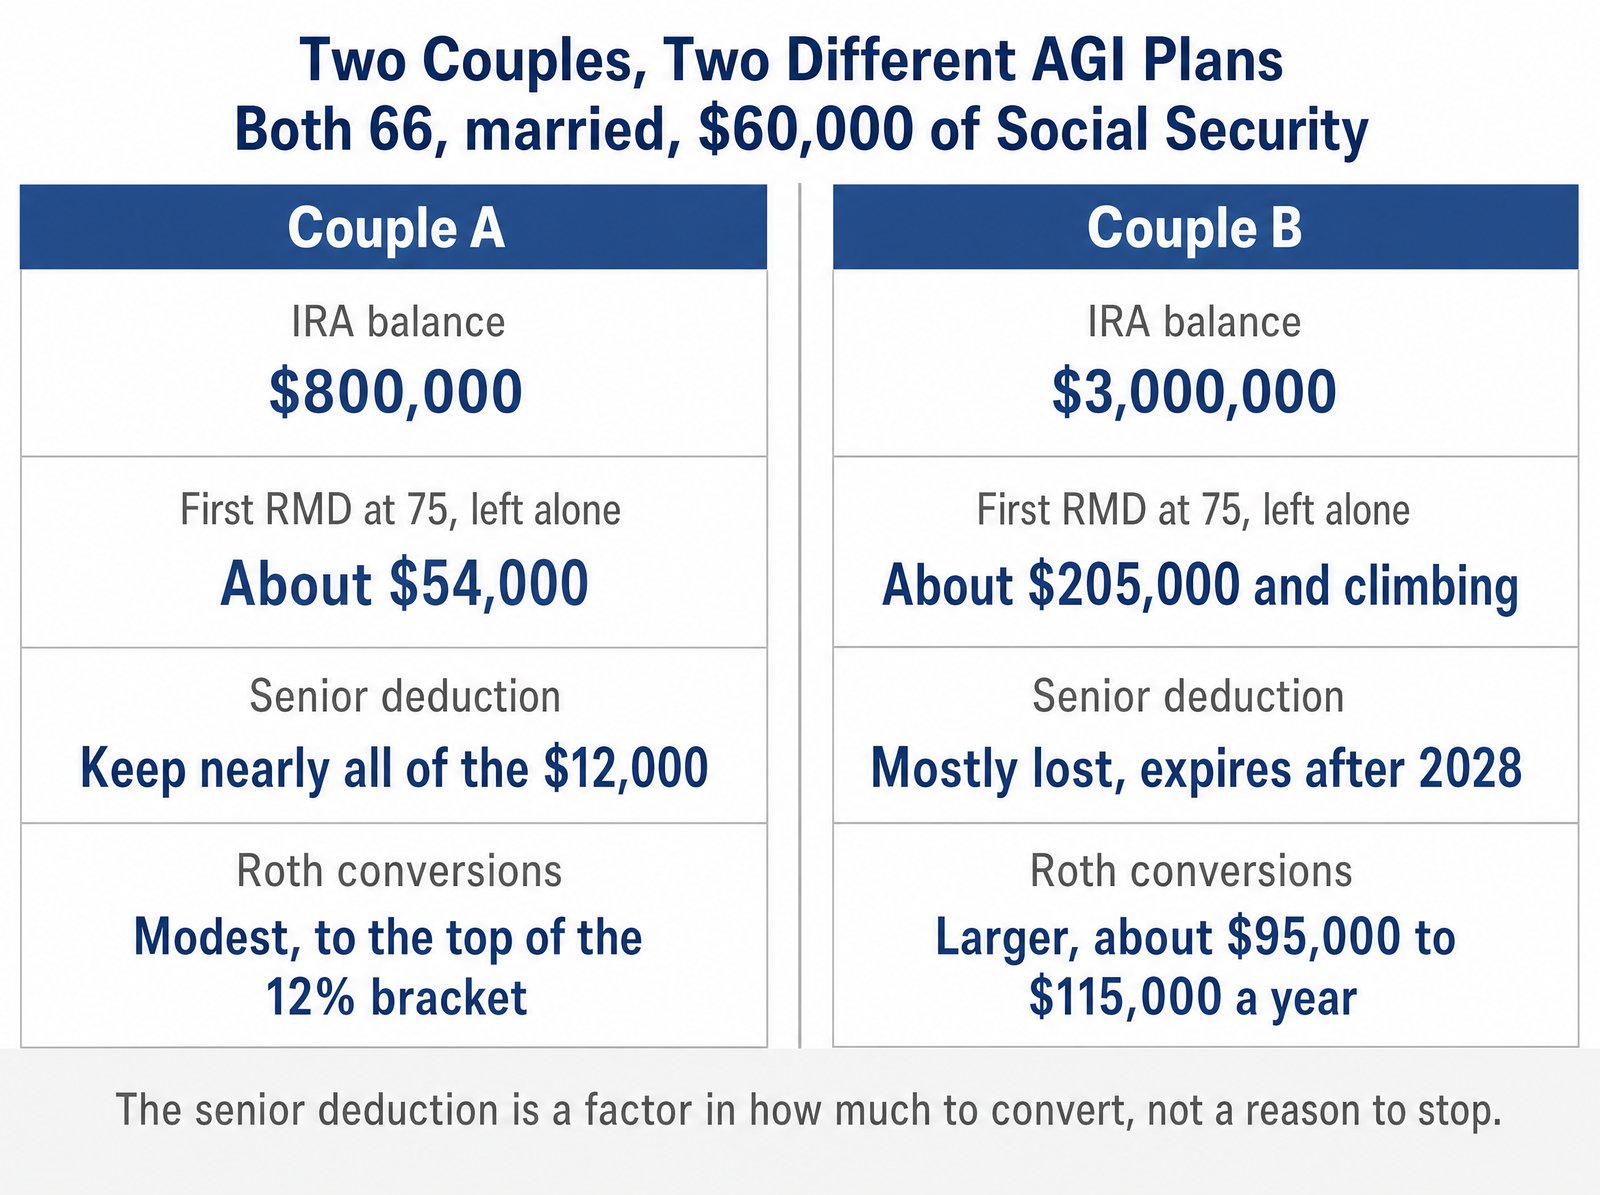
Let me show you why the size of the IRA changes the whole plan. Say you've got two couples, both 66, both filing jointly, both with about $60,000 of combined Social Security.
Couple A has $800,000 in IRAs and $300,000 in a brokerage account.
Left alone, their first RMD at 75 is about $54,000. Add Social Security and they stay under $150,000 of MAGI as long as they are both alive.
For them, lowering AGI is straightforward. Spend from the IRA first, add modest conversions up to the top of the 12% bracket, keep nearly all of the $12,000 senior deduction, and stay far under IRMAA.
Couple B has $3,000,000 in IRAs and the same $300,000 brokerage account.
Left alone, their first RMD at 75 is about $205,000, and it climbs from there on top of Social Security. If one of them passes, the survivor files single with the same RMDs, which is the widow's tax trap.
For them, the senior deduction phaseout at $150,000 is real, but it is not the deciding factor. Spending from the IRA first and converting about $95,000 to $115,000 a year from 66 to 74 costs them most of a $12,000 deduction that expires after 2028 anyway.
Not converting pushes the survivor's top RMD dollars into the 32% bracket from age 81 on. With the conversions, the survivor tops out in the 24% bracket.
We are making a lot of assumptions here, and every case gets its own projection. But the pattern holds: the senior deduction is a factor in how much you convert, not a reason to stop converting.
The deduction goes away in 2029. The RMDs do not.
How We Keep the Number Where It Belongs
We do tax planning as a core service, and AGI is the number at the center of it. The process is the same one we use to stay under the Medicare IRMAA brackets.
First, we review the prior year's return and find where the income came from. Second, we build an estimate for the current year against every line in the table above.
Third, we track it through the year, and every withdrawal, sale, or conversion gets run against the estimate before it happens. Then in the fourth quarter we fine-tune and leave a $5,000 to $10,000 buffer under whichever line matters most.
If you would like to see this done for your situation, our tax planning service is built around it.
Frequently Asked Questions
Does Social Security count toward AGI?
Only the taxable portion does, which can be anywhere from 0% to 85% of your benefit. The taxable portion is set by your combined income for Social Security taxes, which is your AGI plus half of your Social Security plus any tax-exempt interest.
Does a Roth IRA withdrawal count toward AGI?
No, as long as the account has been open five years and you are 59 1/2. Qualified Roth withdrawals do not appear anywhere on the income side of your return, which is what makes the Roth bucket so useful for managing the lines above.
Does a QCD reduce AGI?
Yes, a qualified charitable distribution never enters your income, so it lowers AGI by the full amount given, up to $111,000 per person in 2026. A deductible cash gift does not lower AGI; it only lowers taxable income after AGI is already set.
What is the difference between AGI and MAGI?
MAGI is AGI with a few items added back, and the add-backs change depending on the rule. For IRMAA it is AGI plus tax-exempt interest; for the senior deduction it is AGI plus excluded foreign income, which for most retirees means MAGI and AGI are the same number or within a few hundred dollars.
Does the standard deduction lower AGI?
No, the standard deduction comes off after AGI to get taxable income. It helps with your tax bracket and the 0% capital gains line, but it does nothing for Social Security taxation, the senior deduction phaseout, or IRMAA.
Here's What Matters
- AGI now controls four lines for a retiree: Social Security taxation, the 0% capital gains bracket, the senior deduction phaseout, and Medicare IRMAA
- The generic advice (401(k), HSA, student loan interest) mostly stops working once you retire
- The retiree levers are which bucket you pull from, QCDs, Roth conversion timing, asset location, controlling forced gains, harvesting, and keeping big events in separate years
- Know which line you are managing to this year: the subsidy cliff before 65, the 0% gains line if you are taxable-heavy, the brackets if you are IRA-heavy
- The senior deduction phaseout is a factor in sizing Roth conversions, not a reason to skip them. It expires after 2028; RMDs do not
- Build the projection before the withdrawal, not after, and keep a $5,000 to $10,000 buffer under the line that matters
Gudorf Financial Group is a fee-only, fiduciary retirement planning firm based in Dayton, Ohio. We serve clients locally and virtually nationwide.
Article References
- "401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500." Internal Revenue Service. November 2025.
- "Retirement Topics: Catch-Up Contributions." Internal Revenue Service. Accessed October 2026.
- "Income Taxes and Your Social Security Benefit." Social Security Administration. Accessed October 2026.
- "2026 Medicare IRMAA Premium MAGI Brackets." The Finance Buff. Accessed October 2026.
- "Enhanced Premium Tax Credit and 2026 Exchange Premiums: Frequently Asked Questions." Congressional Research Service. Accessed October 2026.